Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Automotive Magnesium Alloy by Alloy Type (AZ Series Magnesium Alloys (AZ31, AZ91, etc.), AM Series Magnesium Alloys (AM50, AM60, etc.), AE Series Magnesium Alloys, ZK Series Magnesium Alloys, Others), by Component Type (Instrument Panel Structures, Steering Wheels, Seat Frames, Transmission Housings, Engine Cradles, Dashboard Supports, Door Frames, Liftgates & Tailgates, Battery Enclosures, Others), by Application (Powertrain Components, Chassis Components, Interior Components, Structural Body Components, Electric Vehicle Battery Structures, Others), by Distribution Channel (OEM, Aftermarket), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 2, 2026|Base Year : 2025|Pages : 106
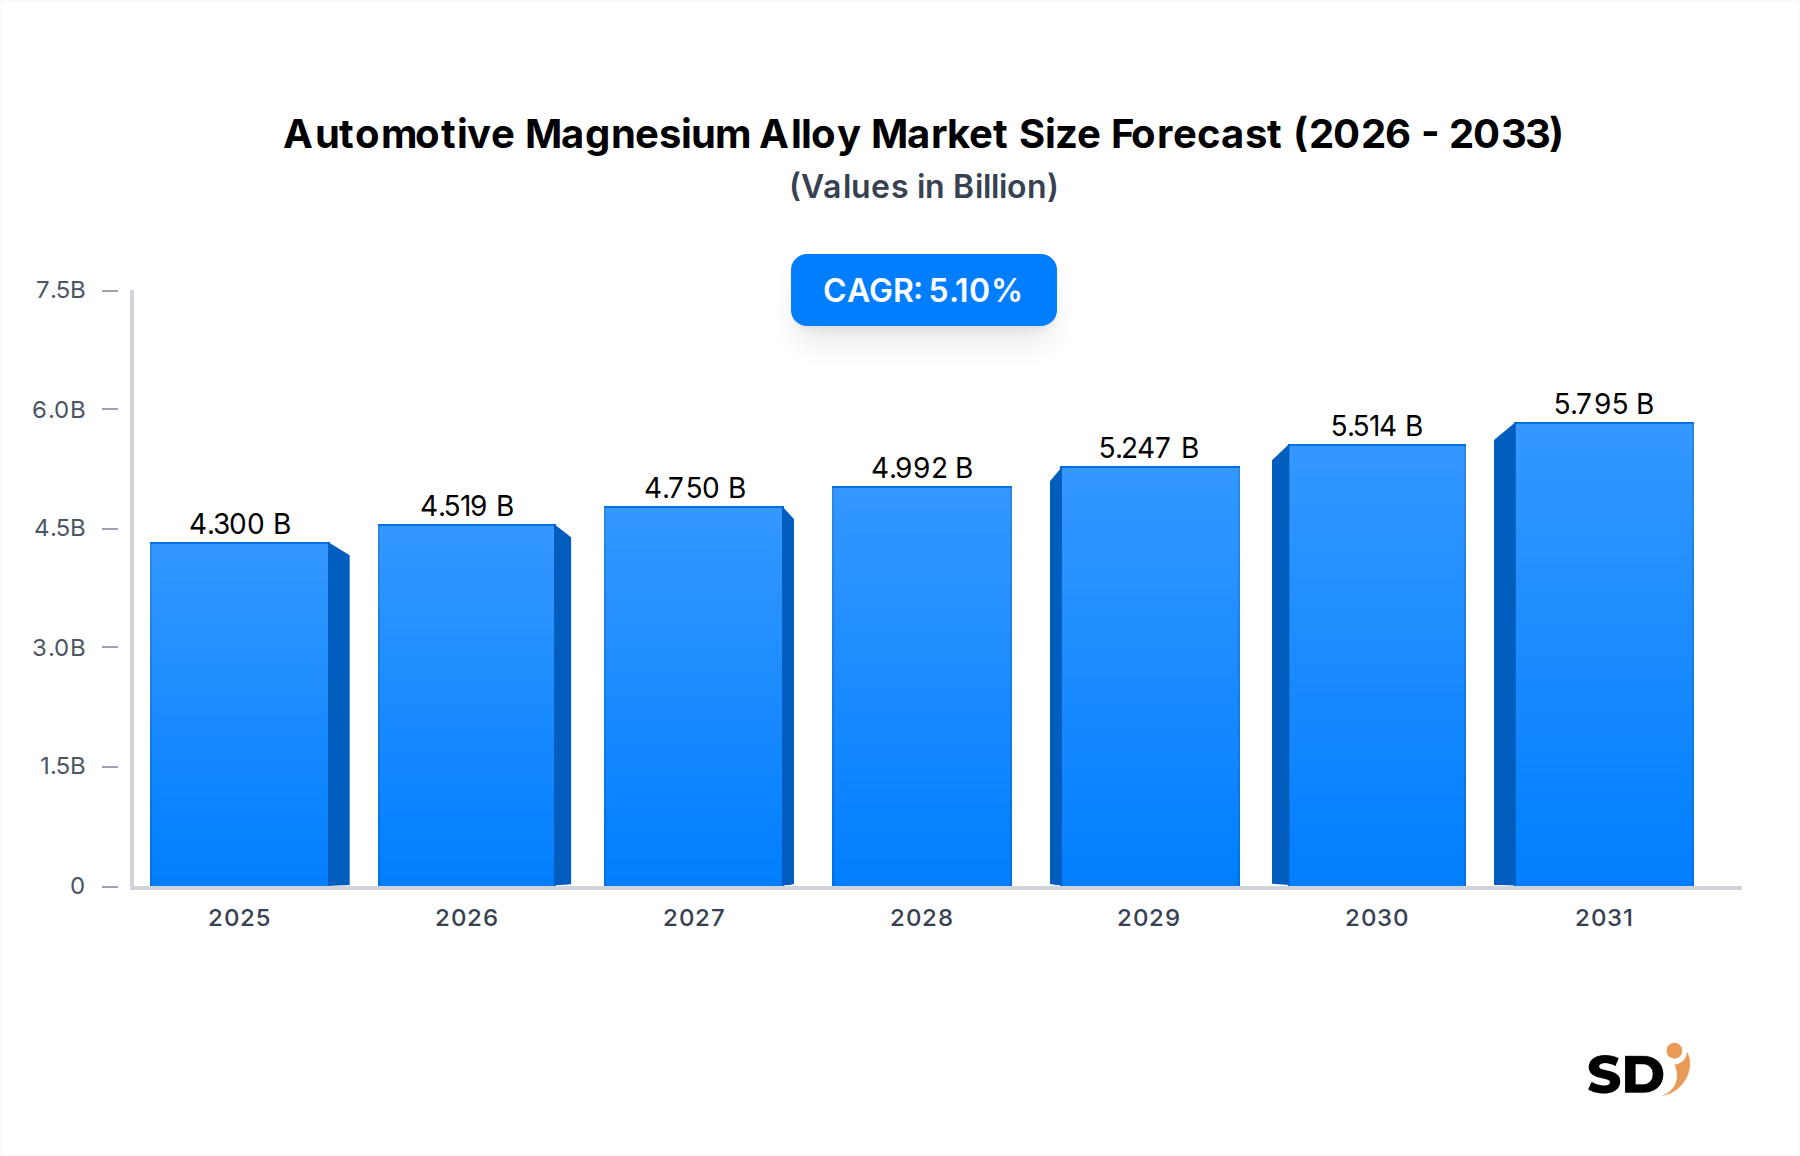
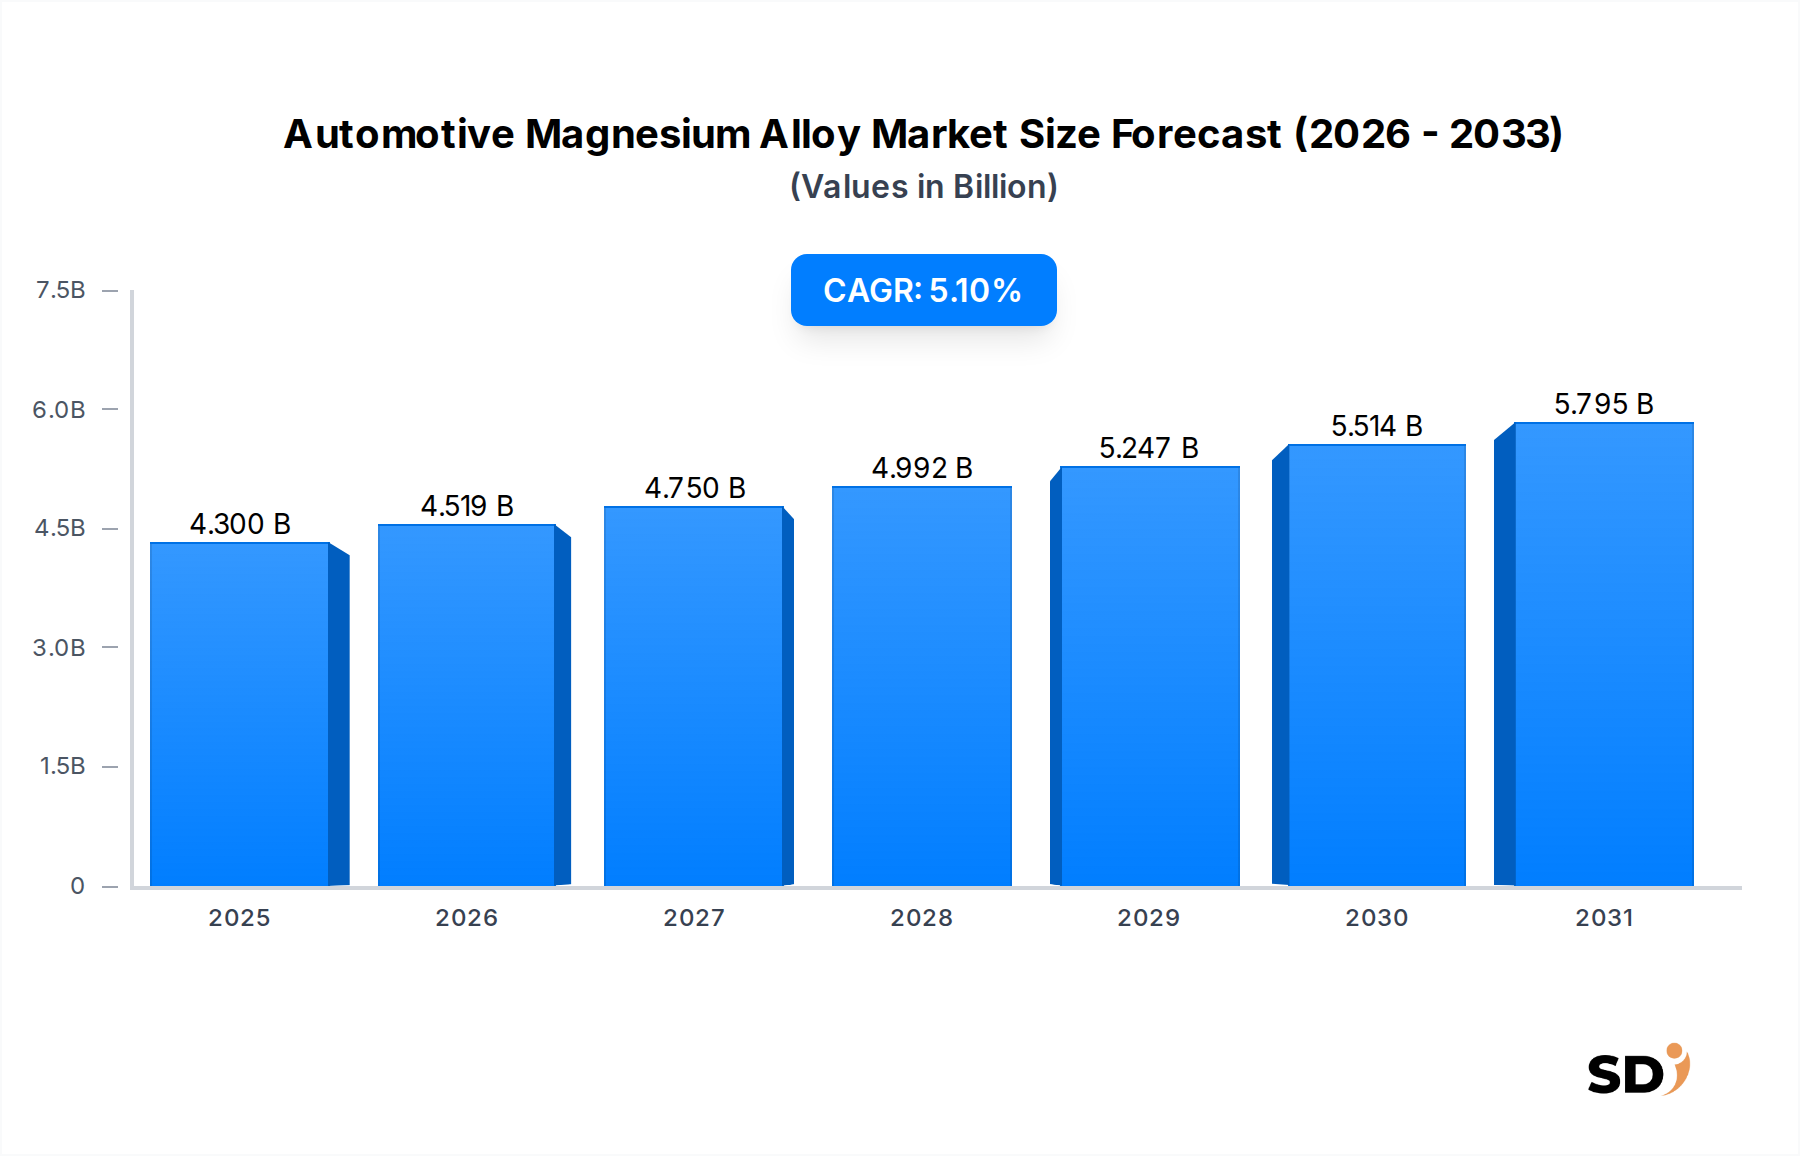
The Global Automotive Magnesium Alloy Market, valued at an estimated $4.3 billion in 2023, is poised for significant expansion, projecting to reach approximately $7.07 billion by 2033, exhibiting a robust Compound Annual Growth Rate (CAGR) of 5.1% over the forecast period. This growth trajectory is fundamentally driven by the automotive industry's relentless pursuit of lightweighting solutions, crucial for enhancing fuel efficiency in internal combustion engine (ICE) vehicles and extending range in electric vehicles (EVs). Stricter global emissions regulations, such as Euro 7 and CAFE standards, compel automakers to integrate advanced materials that offer superior strength-to-weight ratios. Magnesium alloys, with a density approximately two-thirds that of aluminum and one-quarter of steel, offer a compelling proposition for weight reduction across various automotive components.
Automotive Magnesium Alloy Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.300 B
2025
4.519 B
2026
4.750 B
2027
4.992 B
2028
5.247 B
2029
5.514 B
2030
5.795 B
2031
The demand landscape is further shaped by the burgeoning Electric Vehicle Components Market, where magnesium alloys play a pivotal role in battery enclosures, motor housings, and structural elements, mitigating the weight penalty associated with large battery packs. While challenges persist, including corrosion susceptibility and higher raw material costs compared to traditional materials, continuous advancements in alloy formulation, surface treatment technologies, and manufacturing processes are expanding their applicability. The market is also benefiting from improved Die Casting Market techniques, which reduce production complexities and costs. Geographically, Asia Pacific is anticipated to remain a dominant force, driven by high automotive production volumes and increasing EV adoption, while North America and Europe are expected to see steady growth fueled by regulatory mandates and technological integration. The overall outlook for the Automotive Magnesium Alloy Market remains positive, underpinned by macro-economic trends favoring sustainable mobility and material innovation.
Structural Body Components Driving the Automotive Magnesium Alloy Market
Within the Automotive Magnesium Alloy Market, the structural body components segment, encompassing elements such as instrument panel structures, seat frames, door frames, and battery enclosures, emerges as a dominant revenue contributor. The criticality of lightweighting in these high-volume components directly translates into enhanced vehicle performance, improved fuel economy, and crucially, extended range for electric vehicles. Magnesium alloys offer an unparalleled strength-to-weight ratio, making them ideal for applications where mass reduction is paramount without compromising structural integrity or safety. For instance, a typical magnesium instrument panel support beam can be up to 30-40% lighter than its aluminum counterpart, delivering significant savings across the vehicle's total mass.
The dominance of this segment is sustained by several factors. Firstly, the imperative to meet stringent crash safety standards while simultaneously reducing vehicle weight pushes manufacturers towards advanced lightweight materials. Magnesium alloys provide excellent energy absorption characteristics, contributing to passive safety. Secondly, the rapid electrification of the global automotive fleet fuels demand for innovative solutions for battery enclosures and EV platforms, where magnesium alloys can contribute to significant weight reduction, thereby offsetting the inherent mass of battery packs. Leading players such as Meridian Lightweight Technologies Inc. and GF Casting Solutions AG have invested heavily in R&D for advanced casting techniques, enabling the production of complex, large-format structural components with high precision. While the initial material cost for magnesium is often higher than steel or aluminum, the system-level benefits—including improved performance, reduced emissions, and potential for downsizing other components—justify its adoption. As the Automotive Manufacturing Market continues its transformation towards lighter, more efficient vehicles, the structural body components segment is expected to maintain its leading position, further integrating magnesium alloys into next-generation vehicle architectures and contributing significantly to the broader Lightweight Materials Market.
Regulatory & Sustainability Mandates as Key Drivers in the Automotive Magnesium Alloy Market
The Automotive Magnesium Alloy Market is significantly propelled by an confluence of stringent regulatory mandates and an industry-wide drive towards enhanced sustainability. A primary driver is the global tightening of emission standards, such as the EU's Euro 7 proposals and North America's Corporate Average Fuel Economy (CAFE) standards, which compel automakers to drastically reduce CO2 emissions and improve fuel efficiency. Each 10% reduction in vehicle weight can lead to a 5-7% improvement in fuel economy, directly translating into lower emissions. The high strength-to-weight ratio of magnesium alloys makes them a critical material choice for achieving these targets, particularly when compared to denser conventional materials like steel or even aluminum.
Secondly, the escalating demand within the Electric Vehicle Components Market necessitates substantial lightweighting to counteract the mass of large battery systems, directly influencing vehicle range and performance. A 100 kg weight reduction in an EV can extend its range by approximately 5-10%, a crucial metric for consumer acceptance. Magnesium alloys offer a compelling solution for components such as battery housings, motor casings, and structural elements, where mass reduction directly impacts EV efficiency. This trend is further supported by the growing Automotive Structural Components Market as automakers seek innovative materials for chassis and body-in-white applications. While the Aluminum Alloy Market remains a strong competitor, the density advantage of magnesium positions it uniquely. The push for circular economy principles within the automotive industry also favors magnesium, owing to its high recyclability potential, though the recycling infrastructure for magnesium alloys is still maturing. This dual pressure of regulatory compliance and sustainability goals is fundamentally reshaping material selection in the Automotive Manufacturing Market, solidifying the role of magnesium alloys as a strategic material.
Competitive Ecosystem of Automotive Magnesium Alloy Market
The Automotive Magnesium Alloy Market features a competitive landscape characterized by specialized material producers, integrated die casters, and diverse component manufacturers. Strategic partnerships and continuous innovation in alloy development and manufacturing processes are key to maintaining market share. The primary focus for these entities is on enhancing material properties, reducing production costs, and expanding application versatility to meet evolving automotive lightweighting demands.
Meridian Lightweight Technologies Inc.: A leading global supplier of magnesium die castings, Meridian is known for its expertise in structural components, including instrument panel beams and front-end carriers, leveraging advanced high-pressure die casting technology to serve major OEMs worldwide.
Dynacast International Inc.: Specializing in precision metal components, Dynacast offers intricate magnesium die castings for various automotive applications, focusing on miniaturization and complex geometries while maintaining high strength and low weight.
STOLFIG: This company is recognized for its capabilities in producing various magnesium alloy components, catering to the automotive sector with a focus on delivering lightweight solutions through advanced casting and fabrication techniques.
GF Casting Solutions AG: A division of Georg Fischer AG, this company is a major supplier of lightweight castings, including magnesium and aluminum components, to the automotive industry, emphasizing innovative solutions for powertrain, chassis, and body applications.
DongGuan Eontec: A significant player in the Asian market, Eontec specializes in magnesium and aluminum alloy die-casting, offering a wide range of components for automotive, electronics, and other industrial applications with a strong focus on high-volume production.
Faw Foundry: As part of the FAW Group, one of China's largest automakers, Faw Foundry contributes significantly to the domestic market, producing various cast components, including those utilizing magnesium alloys for internal vehicle platforms.
Nanjing Yunhai Special Metals: A prominent Chinese producer of magnesium alloys, Yunhai Special Metals is a key supplier of raw materials and semi-finished products, playing a crucial role in the upstream supply chain of the Primary Magnesium Market for automotive applications.
Yinguang Magnesium Industry: Based in China, Yinguang is a comprehensive magnesium enterprise involved in raw magnesium production and various magnesium alloy products, serving both the domestic and international automotive sectors with a focus on quality and cost-effectiveness.
Million and Precision Industrial Holdings: This company focuses on precision engineering and manufacturing, providing specialized magnesium alloy components that demand high accuracy and performance for diverse automotive applications.
Magontec Limited: An international leader in the development and production of magnesium alloys, Magontec specializes in both primary and recycled magnesium products, serving the automotive and aerospace industries with advanced material solutions.
Recent Developments & Milestones in Automotive Magnesium Alloy Market
Recent advancements in the Automotive Magnesium Alloy Market have focused on enhancing material properties, improving manufacturing efficiency, and expanding application scopes, particularly within the context of vehicle electrification.
March 2024: A leading research consortium announced a breakthrough in developing new high-ductility magnesium alloys, specifically designed to address the material's traditional limitations in forming complex shapes at room temperature, potentially reducing production costs for Automotive Structural Components Market.
October 2023: A major Tier 1 supplier launched a new generation of lightweight magnesium seat frames, achieving a 15% weight reduction compared to previous aluminum designs, directly contributing to overall vehicle mass reduction and improved fuel efficiency.
June 2023: Investment increased significantly in advanced Die Casting Market technologies for magnesium, including thixomolding and semi-solid casting, aimed at producing intricate components with superior mechanical properties and reduced porosity for the Automotive Magnesium Alloy Market.
January 2023: Several OEMs began pilot programs integrating magnesium alloy battery enclosures into their next-generation Electric Vehicle Components Market platforms, leveraging the material's excellent thermal dissipation properties and lightweight advantages.
November 2022: Researchers unveiled novel surface treatment techniques that significantly improve the corrosion resistance of magnesium alloys, mitigating a longstanding challenge and broadening their potential applications in exposed automotive environments.
August 2022: Strategic partnerships between Primary Magnesium Market suppliers and automotive component manufacturers were established to secure stable supply chains and drive down material costs through process optimization and economies of scale.
Regional Market Breakdown for Automotive Magnesium Alloy Market
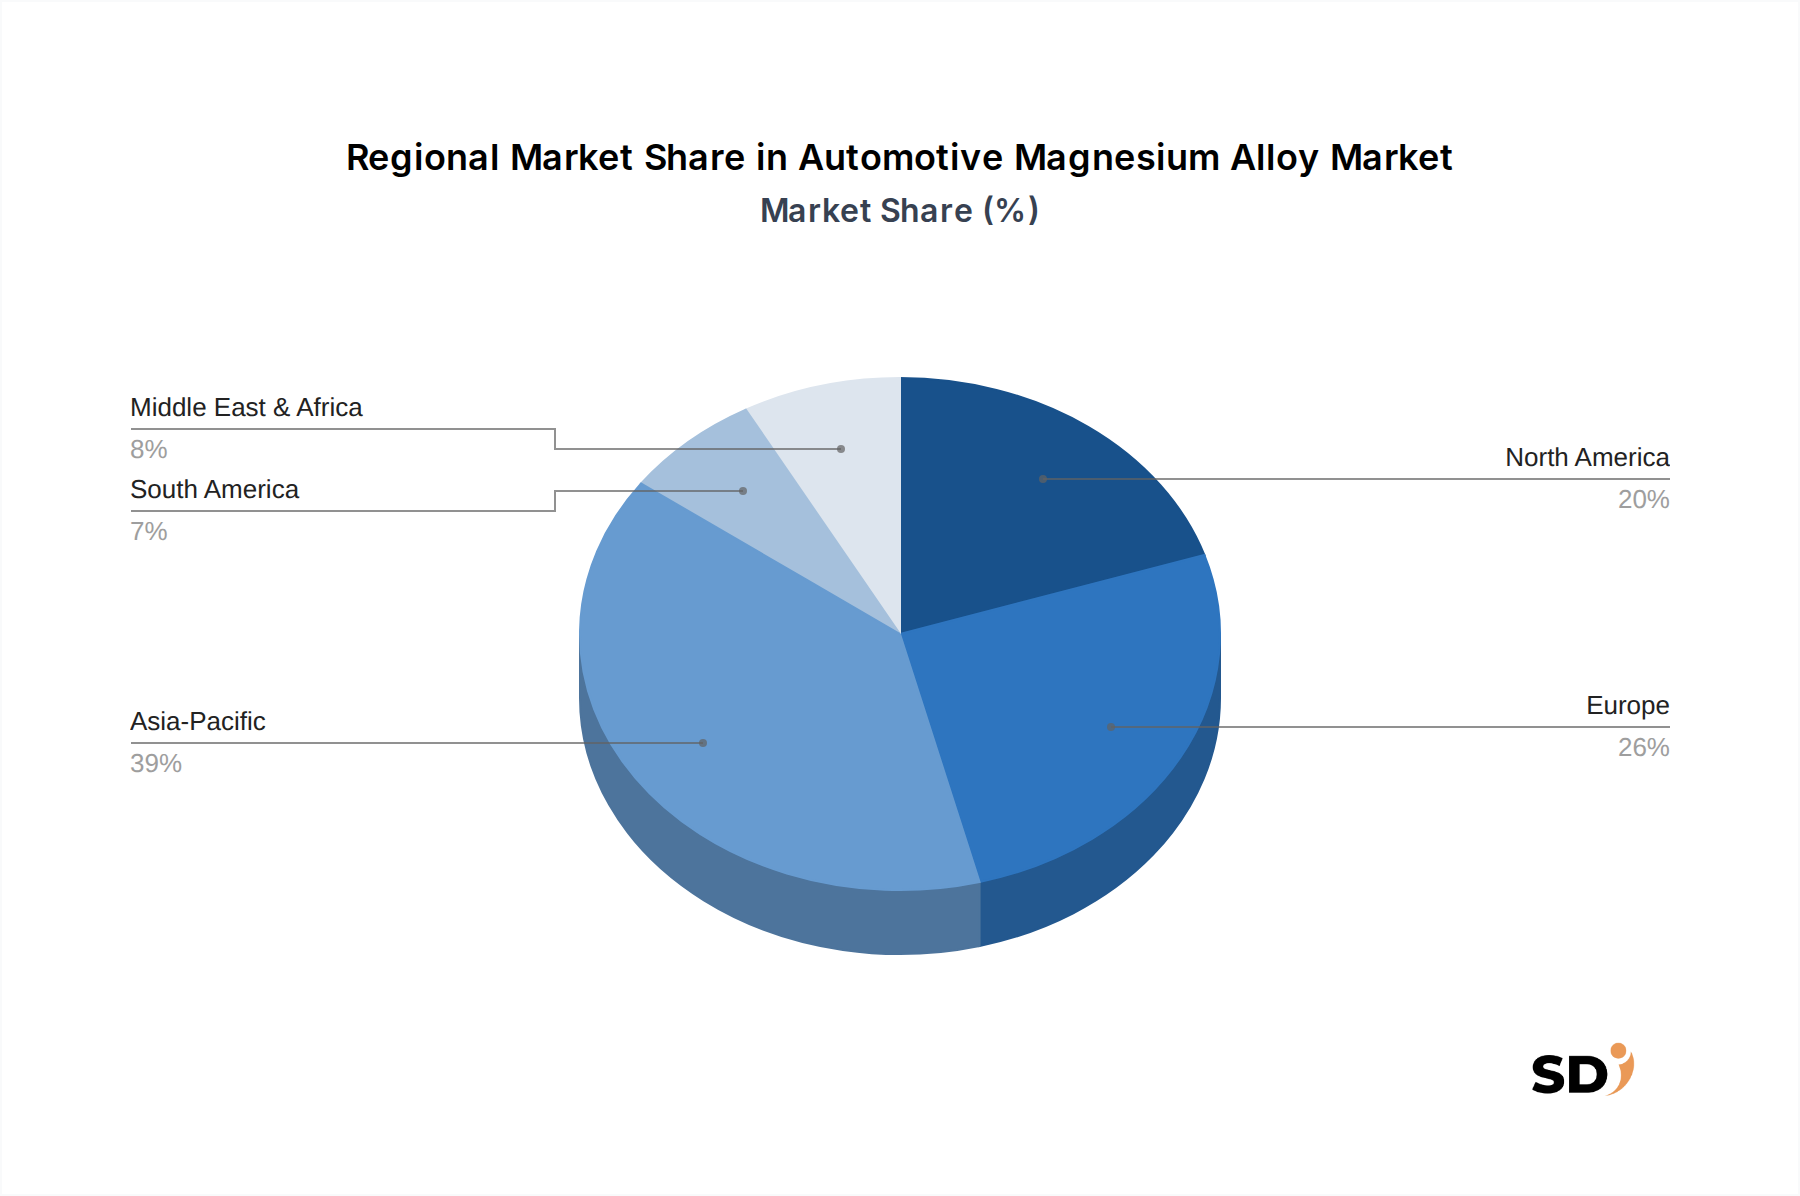
The global Automotive Magnesium Alloy Market exhibits diverse growth dynamics across key regions, driven by varying automotive production volumes, regulatory frameworks, and technological adoption rates. Asia Pacific holds the largest market share and is projected to be the fastest-growing region, primarily fueled by China's dominant position in automotive manufacturing and its aggressive push towards electric vehicles. Countries like China, Japan, and South Korea are major hubs for both traditional automotive and EV production, driving demand for lightweight materials. China's significant contributions to the Primary Magnesium Market also provide a localized advantage.
Europe represents a mature yet robust market, with a strong emphasis on meeting stringent emissions standards, notably Euro 7. This regulatory pressure compels European automakers in Germany, France, and the UK to actively integrate magnesium alloys for lightweighting. While its growth may be steady rather than explosive, the region’s commitment to premium and high-performance vehicles ensures consistent demand. North America, particularly the United States, also demonstrates substantial demand, driven by CAFE standards and the expanding Electric Vehicle Components Market. Automakers in this region are increasingly adopting magnesium for transmission housings, engine cradles, and structural components to enhance fuel economy and EV range.
Conversely, South America and the Middle East & Africa regions currently hold smaller shares. However, rising automotive production and increasing environmental awareness in economies like Brazil and South Africa suggest emerging opportunities. These regions are likely to adopt proven magnesium alloy technologies as their automotive sectors mature and regulatory frameworks align with global standards. Overall, the global market is characterized by a concerted effort to leverage magnesium's lightweight properties to address both environmental mandates and performance expectations across all major automotive manufacturing regions, thereby boosting the broader Advanced Materials Market.
The regulatory and policy landscape exerts a profound influence on the adoption and growth of the Automotive Magnesium Alloy Market. Governments worldwide are implementing increasingly stringent emissions and fuel efficiency standards, directly incentivizing the use of lightweight materials. For instance, in Europe, the proposed Euro 7 emission standards, slated for implementation in the mid-2020s, will place immense pressure on vehicle manufacturers to reduce tailpipe emissions, making weight reduction a critical strategy. Similarly, North America’s Corporate Average Fuel Economy (CAFE) standards mandate continuous improvements in fleet-wide fuel efficiency, driving demand for materials like magnesium alloys that offer superior strength-to-weight ratios compared to steel and aluminum.
Beyond direct emissions, policies promoting electric vehicle adoption, such as tax incentives, subsidies, and charging infrastructure investments, indirectly bolster the Electric Vehicle Components Market and, consequently, the demand for lightweight magnesium alloys in battery enclosures and structural elements. Safety regulations, while not directly mandating material use, often lead to design requirements that can be met more efficiently with lightweight materials without compromising crashworthiness. For example, standards from the National Highway Traffic Safety Administration (NHTSA) in the U.S. require vehicles to meet specific crash performance criteria. Moreover, global initiatives aimed at promoting a circular economy and sustainable manufacturing are encouraging the development of recyclable materials and processes. While magnesium has high recycling potential, policies supporting its collection and reprocessing infrastructure are nascent but critical for long-term market growth. These evolving policies compel automakers to integrate advanced materials, making the Lightweight Materials Market a key focus for innovation.
Supply Chain & Raw Material Dynamics for Automotive Magnesium Alloy Market
The supply chain and raw material dynamics for the Automotive Magnesium Alloy Market are intrinsically linked to the global Primary Magnesium Market. Magnesium, as the lightest structural metal, is primarily sourced from magnesite ore or seawater/brine through energy-intensive electrolysis or thermal reduction processes (e.g., Pidgeon process). China dominates global primary magnesium production, accounting for over 85% of the world's supply. This high concentration in a single geographical region introduces significant supply chain risks, including potential disruptions from trade policies, geopolitical tensions, and environmental regulations impacting production within China.
Price volatility of primary magnesium is a notable concern for automotive manufacturers. Fluctuations are often driven by energy costs (especially electricity, crucial for electrolysis), environmental compliance costs, and global industrial demand. For instance, recent energy crises have seen spikes in magnesium prices, directly impacting the cost structure of magnesium alloy components. Beyond pure magnesium, alloying elements like aluminum (for AZ series alloys like AZ91), zinc (for ZK series), and rare earth elements (for AE series) are also critical inputs. The sourcing and pricing of these secondary raw materials can also influence the overall cost and availability of specific magnesium alloy types. The industry is actively exploring diversification of magnesium sourcing and enhancing recycling capabilities to mitigate these risks. While the Aluminum Alloy Market benefits from a more diversified and mature recycling infrastructure, the development of efficient magnesium scrap recycling systems is crucial for ensuring long-term material sustainability and reducing reliance on primary production, thereby impacting the overall Advanced Materials Market.
Automotive Magnesium Alloy Segmentation
1. Alloy Type
1.1. AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
1.2. AM Series Magnesium Alloys (AM50, AM60, etc.)
1.3. AE Series Magnesium Alloys
1.4. ZK Series Magnesium Alloys
1.5. Others
2. Component Type
2.1. Instrument Panel Structures
2.2. Steering Wheels
2.3. Seat Frames
2.4. Transmission Housings
2.5. Engine Cradles
2.6. Dashboard Supports
2.7. Door Frames
2.8. Liftgates & Tailgates
2.9. Battery Enclosures
2.10. Others
3. Application
3.1. Powertrain Components
3.2. Chassis Components
3.3. Interior Components
3.4. Structural Body Components
3.5. Electric Vehicle Battery Structures
3.6. Others
4. Distribution Channel
4.1. OEM
4.2. Aftermarket
Automotive Magnesium Alloy Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Automotive Magnesium Alloy REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.1% from 2020-2034
Segmentation
By Alloy Type
AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
AM Series Magnesium Alloys (AM50, AM60, etc.)
AE Series Magnesium Alloys
ZK Series Magnesium Alloys
Others
By Component Type
Instrument Panel Structures
Steering Wheels
Seat Frames
Transmission Housings
Engine Cradles
Dashboard Supports
Door Frames
Liftgates & Tailgates
Battery Enclosures
Others
By Application
Powertrain Components
Chassis Components
Interior Components
Structural Body Components
Electric Vehicle Battery Structures
Others
By Distribution Channel
OEM
Aftermarket
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Alloy Type
5.1.1. AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
5.1.2. AM Series Magnesium Alloys (AM50, AM60, etc.)
5.1.3. AE Series Magnesium Alloys
5.1.4. ZK Series Magnesium Alloys
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Component Type
5.2.1. Instrument Panel Structures
5.2.2. Steering Wheels
5.2.3. Seat Frames
5.2.4. Transmission Housings
5.2.5. Engine Cradles
5.2.6. Dashboard Supports
5.2.7. Door Frames
5.2.8. Liftgates & Tailgates
5.2.9. Battery Enclosures
5.2.10. Others
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Powertrain Components
5.3.2. Chassis Components
5.3.3. Interior Components
5.3.4. Structural Body Components
5.3.5. Electric Vehicle Battery Structures
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Distribution Channel
5.4.1. OEM
5.4.2. Aftermarket
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. South America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Alloy Type
6.1.1. AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
6.1.2. AM Series Magnesium Alloys (AM50, AM60, etc.)
6.1.3. AE Series Magnesium Alloys
6.1.4. ZK Series Magnesium Alloys
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Component Type
6.2.1. Instrument Panel Structures
6.2.2. Steering Wheels
6.2.3. Seat Frames
6.2.4. Transmission Housings
6.2.5. Engine Cradles
6.2.6. Dashboard Supports
6.2.7. Door Frames
6.2.8. Liftgates & Tailgates
6.2.9. Battery Enclosures
6.2.10. Others
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Powertrain Components
6.3.2. Chassis Components
6.3.3. Interior Components
6.3.4. Structural Body Components
6.3.5. Electric Vehicle Battery Structures
6.3.6. Others
6.4. Market Analysis, Insights and Forecast - by Distribution Channel
6.4.1. OEM
6.4.2. Aftermarket
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Alloy Type
7.1.1. AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
7.1.2. AM Series Magnesium Alloys (AM50, AM60, etc.)
7.1.3. AE Series Magnesium Alloys
7.1.4. ZK Series Magnesium Alloys
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Component Type
7.2.1. Instrument Panel Structures
7.2.2. Steering Wheels
7.2.3. Seat Frames
7.2.4. Transmission Housings
7.2.5. Engine Cradles
7.2.6. Dashboard Supports
7.2.7. Door Frames
7.2.8. Liftgates & Tailgates
7.2.9. Battery Enclosures
7.2.10. Others
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Powertrain Components
7.3.2. Chassis Components
7.3.3. Interior Components
7.3.4. Structural Body Components
7.3.5. Electric Vehicle Battery Structures
7.3.6. Others
7.4. Market Analysis, Insights and Forecast - by Distribution Channel
7.4.1. OEM
7.4.2. Aftermarket
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Alloy Type
8.1.1. AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
8.1.2. AM Series Magnesium Alloys (AM50, AM60, etc.)
8.1.3. AE Series Magnesium Alloys
8.1.4. ZK Series Magnesium Alloys
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Component Type
8.2.1. Instrument Panel Structures
8.2.2. Steering Wheels
8.2.3. Seat Frames
8.2.4. Transmission Housings
8.2.5. Engine Cradles
8.2.6. Dashboard Supports
8.2.7. Door Frames
8.2.8. Liftgates & Tailgates
8.2.9. Battery Enclosures
8.2.10. Others
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Powertrain Components
8.3.2. Chassis Components
8.3.3. Interior Components
8.3.4. Structural Body Components
8.3.5. Electric Vehicle Battery Structures
8.3.6. Others
8.4. Market Analysis, Insights and Forecast - by Distribution Channel
8.4.1. OEM
8.4.2. Aftermarket
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Alloy Type
9.1.1. AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
9.1.2. AM Series Magnesium Alloys (AM50, AM60, etc.)
9.1.3. AE Series Magnesium Alloys
9.1.4. ZK Series Magnesium Alloys
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Component Type
9.2.1. Instrument Panel Structures
9.2.2. Steering Wheels
9.2.3. Seat Frames
9.2.4. Transmission Housings
9.2.5. Engine Cradles
9.2.6. Dashboard Supports
9.2.7. Door Frames
9.2.8. Liftgates & Tailgates
9.2.9. Battery Enclosures
9.2.10. Others
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Powertrain Components
9.3.2. Chassis Components
9.3.3. Interior Components
9.3.4. Structural Body Components
9.3.5. Electric Vehicle Battery Structures
9.3.6. Others
9.4. Market Analysis, Insights and Forecast - by Distribution Channel
9.4.1. OEM
9.4.2. Aftermarket
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Alloy Type
10.1.1. AZ Series Magnesium Alloys (AZ31, AZ91, etc.)
10.1.2. AM Series Magnesium Alloys (AM50, AM60, etc.)
10.1.3. AE Series Magnesium Alloys
10.1.4. ZK Series Magnesium Alloys
10.1.5. Others
10.2. Market Analysis, Insights and Forecast - by Component Type
10.2.1. Instrument Panel Structures
10.2.2. Steering Wheels
10.2.3. Seat Frames
10.2.4. Transmission Housings
10.2.5. Engine Cradles
10.2.6. Dashboard Supports
10.2.7. Door Frames
10.2.8. Liftgates & Tailgates
10.2.9. Battery Enclosures
10.2.10. Others
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Powertrain Components
10.3.2. Chassis Components
10.3.3. Interior Components
10.3.4. Structural Body Components
10.3.5. Electric Vehicle Battery Structures
10.3.6. Others
10.4. Market Analysis, Insights and Forecast - by Distribution Channel
10.4.1. OEM
10.4.2. Aftermarket
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Meridian Lightweight Technologies Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Dynacast International Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. STOLFIG
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. GF Casting Solutions AG
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. DongGuan Eontec
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Faw Foundry
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Nanjing Yunhai Special Metals
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Yinguang Magnesium Industry
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Million and Precision Industrial Holdings
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Magontec Limited
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. RIMA Industrial S.A.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Georg Fischer AG
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Ryobi Limited
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Others
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Magnesium Alloy Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Automotive Magnesium Alloy Revenue (billion), by Alloy Type 2026 & 2034
Figure 3: North America Automotive Magnesium Alloy Revenue Share (%), by Alloy Type 2026 & 2034
Figure 4: North America Automotive Magnesium Alloy Revenue (billion), by Component Type 2026 & 2034
Figure 5: North America Automotive Magnesium Alloy Revenue Share (%), by Component Type 2026 & 2034
Figure 6: North America Automotive Magnesium Alloy Revenue (billion), by Application 2026 & 2034
Figure 7: North America Automotive Magnesium Alloy Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Automotive Magnesium Alloy Revenue (billion), by Distribution Channel 2026 & 2034
Figure 9: North America Automotive Magnesium Alloy Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 10: North America Automotive Magnesium Alloy Revenue (billion), by Country 2026 & 2034
Figure 11: North America Automotive Magnesium Alloy Revenue Share (%), by Country 2026 & 2034
Figure 12: South America Automotive Magnesium Alloy Revenue (billion), by Alloy Type 2026 & 2034
Figure 13: South America Automotive Magnesium Alloy Revenue Share (%), by Alloy Type 2026 & 2034
Figure 14: South America Automotive Magnesium Alloy Revenue (billion), by Component Type 2026 & 2034
Figure 15: South America Automotive Magnesium Alloy Revenue Share (%), by Component Type 2026 & 2034
Figure 16: South America Automotive Magnesium Alloy Revenue (billion), by Application 2026 & 2034
Figure 17: South America Automotive Magnesium Alloy Revenue Share (%), by Application 2026 & 2034
Figure 18: South America Automotive Magnesium Alloy Revenue (billion), by Distribution Channel 2026 & 2034
Figure 19: South America Automotive Magnesium Alloy Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 20: South America Automotive Magnesium Alloy Revenue (billion), by Country 2026 & 2034
Figure 21: South America Automotive Magnesium Alloy Revenue Share (%), by Country 2026 & 2034
Figure 22: Europe Automotive Magnesium Alloy Revenue (billion), by Alloy Type 2026 & 2034
Figure 23: Europe Automotive Magnesium Alloy Revenue Share (%), by Alloy Type 2026 & 2034
Figure 24: Europe Automotive Magnesium Alloy Revenue (billion), by Component Type 2026 & 2034
Figure 25: Europe Automotive Magnesium Alloy Revenue Share (%), by Component Type 2026 & 2034
Figure 26: Europe Automotive Magnesium Alloy Revenue (billion), by Application 2026 & 2034
Figure 27: Europe Automotive Magnesium Alloy Revenue Share (%), by Application 2026 & 2034
Figure 28: Europe Automotive Magnesium Alloy Revenue (billion), by Distribution Channel 2026 & 2034
Figure 29: Europe Automotive Magnesium Alloy Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 30: Europe Automotive Magnesium Alloy Revenue (billion), by Country 2026 & 2034
Figure 31: Europe Automotive Magnesium Alloy Revenue Share (%), by Country 2026 & 2034
Figure 32: Middle East & Africa Automotive Magnesium Alloy Revenue (billion), by Alloy Type 2026 & 2034
Figure 33: Middle East & Africa Automotive Magnesium Alloy Revenue Share (%), by Alloy Type 2026 & 2034
Figure 34: Middle East & Africa Automotive Magnesium Alloy Revenue (billion), by Component Type 2026 & 2034
Figure 35: Middle East & Africa Automotive Magnesium Alloy Revenue Share (%), by Component Type 2026 & 2034
Figure 36: Middle East & Africa Automotive Magnesium Alloy Revenue (billion), by Application 2026 & 2034
Figure 37: Middle East & Africa Automotive Magnesium Alloy Revenue Share (%), by Application 2026 & 2034
Figure 38: Middle East & Africa Automotive Magnesium Alloy Revenue (billion), by Distribution Channel 2026 & 2034
Figure 39: Middle East & Africa Automotive Magnesium Alloy Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 40: Middle East & Africa Automotive Magnesium Alloy Revenue (billion), by Country 2026 & 2034
Figure 41: Middle East & Africa Automotive Magnesium Alloy Revenue Share (%), by Country 2026 & 2034
Figure 42: Asia Pacific Automotive Magnesium Alloy Revenue (billion), by Alloy Type 2026 & 2034
Figure 43: Asia Pacific Automotive Magnesium Alloy Revenue Share (%), by Alloy Type 2026 & 2034
Figure 44: Asia Pacific Automotive Magnesium Alloy Revenue (billion), by Component Type 2026 & 2034
Figure 45: Asia Pacific Automotive Magnesium Alloy Revenue Share (%), by Component Type 2026 & 2034
Figure 46: Asia Pacific Automotive Magnesium Alloy Revenue (billion), by Application 2026 & 2034
Figure 47: Asia Pacific Automotive Magnesium Alloy Revenue Share (%), by Application 2026 & 2034
Figure 48: Asia Pacific Automotive Magnesium Alloy Revenue (billion), by Distribution Channel 2026 & 2034
Figure 49: Asia Pacific Automotive Magnesium Alloy Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 50: Asia Pacific Automotive Magnesium Alloy Revenue (billion), by Country 2026 & 2034
Figure 51: Asia Pacific Automotive Magnesium Alloy Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Automotive Magnesium Alloy Revenue billion Forecast, by Alloy Type 2020 & 2034
Table 2: Automotive Magnesium Alloy Revenue billion Forecast, by Component Type 2020 & 2034
Table 58: Rest of Asia Pacific Automotive Magnesium Alloy Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research forms the cornerstone of our market estimation and validation, constituting approximately 75% of our overall research efforts for the "Automotive Magnesium Alloy" market report. This extensive engagement provides real-time, ground-level insights directly from industry participants, ensuring the most current and accurate understanding of market dynamics, emerging trends, technological advancements, and competitive landscapes. Our primary research methodology involves in-depth, structured interviews conducted across various geographies including North America, Europe, Asia Pacific, South America, and Middle East & Africa.
Key participants interviewed in this study include:
Company Types:
Magnesium Alloy Primary Producers
Automotive Die Casting & Foundries
Automotive Tier-1 Component Suppliers
Major Automotive Original Equipment Manufacturers (OEMs)
Specialty Magnesium Component Fabricators
Job Designations/Stakeholders:
Head of Materials Engineering / Senior Materials Scientist
VP of Procurement / Supply Chain Director
Product Development Manager / Application Engineer
Business Development Manager / Sales Director
These interactions are carefully structured to gather both qualitative and quantitative data, offering perspectives on market size, growth drivers, restraints, opportunities, competitive strategies, and future outlooks for automotive magnesium alloys across different alloy types, component types, applications, and distribution channels. The interviews are conducted through a blend of telephonic discussions, virtual meetings, and, where feasible, face-to-face interactions.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of Materials Engineering / Senior Materials Scientist
30%
VP of Procurement / Supply Chain Director
25%
Product Development Manager / Application Engineer
25%
Business Development Manager / Sales Director
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Magnesium Alloy Primary Producers
25%
Automotive Die Casting & Foundries
20%
Automotive Tier-1 Component Suppliers
30%
Major Automotive Original Equipment Manufacturers (OEMs)
20%
Specialty Magnesium Component Fabricators
5%
Secondary Research & Industry Benchmarking
Secondary research accounts for approximately 25% of our total research methodology and serves to build a robust foundation for primary research, validate initial hypotheses, and provide comprehensive industry benchmarking. This phase involves a rigorous analysis of publicly available and proprietary data sources. Our research adheres strictly to using credible and authoritative sources, excluding data from other market research websites.
Key data sources leveraged include:
Financial Databases & Business Intelligence Platforms: Bloomberg, Factiva, Hoovers, and PitchBook are utilized to gather company financials, market performance data, investment trends, and strategic initiatives of key players in the automotive and magnesium alloy sectors.
Government & Regulatory Publications: Official government reports, statistical data, and policy documents from relevant bodies provide insights into automotive production, emissions standards, lightweighting initiatives, and material regulations. Examples include data from the U.S. Department of Commerce, European Commission, and national statistical offices.
Trade Associations & Industry Bodies: Publications, white papers, conference proceedings, and membership directories from globally recognized industry associations offer specialized data and expert perspectives on material trends, manufacturing processes, and market forecasts.
U.S. Department of Energy (DOE) - specifically relevant for EV lightweighting and battery structures initiatives: https://www.energy.gov/
Company Annual Reports & Investor Presentations: These provide detailed financial performance, operational data, product portfolios, and strategic outlooks of key manufacturers and suppliers in the value chain.
Technical Journals & Publications: Scientific and engineering literature offers insights into material science advancements, processing techniques, and application developments for magnesium alloys in automotive components.
Demand Modeling & Market Estimation
Our approach to market sizing and forecasting is highly robust, employing a combination of top-down and bottom-up methodologies alongside multi-level data triangulation to ensure maximum accuracy. The forecast period spans from 2026 to 2034, projecting the market trajectory for automotive magnesium alloys.
Top-Down Approach: This method begins with analyzing the overall automotive production volumes and growth trends at a macro level, then segmenting down by vehicle type, region, and finally estimating the potential for magnesium alloy penetration based on industry trends and regulatory drivers (e.g., fuel efficiency, emissions targets).
Bottom-Up Approach: This detailed method involves aggregating data from granular levels. Key metrics and variables used for bottom-up calculation include:
Automotive production volumes by vehicle type (e.g., passenger cars, commercial vehicles, electric vehicles) and regional production forecasts.
Average magnesium alloy content (in kg) per vehicle for specific component types (e.g., instrument panel structures, transmission housings, battery enclosures), informed by current usage and future design trends.
Penetration rate of magnesium alloys in target automotive components, considering material substitution trends and cost-benefit analyses.
Average selling price (ASP) per kilogram for different magnesium alloy types (AZ Series, AM Series, AE Series, ZK Series, Others) across various application segments.
Forecasted demand for Electric Vehicle Battery Structures in terms of lightweight material requirements.
Multi-Level Data Triangulation: This critical step involves cross-referencing and validating data points obtained from primary interviews with insights from secondary research, and comparing results from both top-down and bottom-up models. This iterative process helps in resolving discrepancies, refining assumptions, and arriving at a highly corroborated market size and forecast for all segments, including Alloy Type, Component Type, Application, Distribution Channel, and all specified geographical regions.
Data Accuracy & Quality Check
We are committed to delivering the highest quality market intelligence. Our stringent data validation processes ensure an estimated data accuracy level of 85-90%. Every data point, market estimate, and forecast undergoes rigorous scrutiny and cross-validation through multiple sources and expert opinions. An independent panel of industry experts periodically reviews our methodologies and findings to maintain objectivity and analytical rigor.
Furthermore, to ensure the utmost relevance and currency, every report is updated up to the date of purchase. This guarantees that clients receive the most recent market dynamics, competitive developments, and technological shifts impacting the Automotive Magnesium Alloy market.
Frequently Asked Questions
1. What primary growth drivers and demand catalysts influence the Automotive Magnesium Alloy market?
The market is driven by increasing demand for lightweight materials to enhance fuel efficiency and reduce emissions across the automotive sector. Key catalysts include the expansion of electric vehicle (EV) production, specifically for battery structures and component types like instrument panel structures and powertrain components, aiming to extend range and improve performance.
2. What is the current investment activity and venture capital interest in the Automotive Magnesium Alloy market?
While specific funding rounds are not detailed, companies like Meridian Lightweight Technologies Inc. and Dynacast International Inc. actively invest in R&D and production capabilities to meet evolving automotive lightweighting demands. Strategic investments focus on advanced alloy types, such as AZ and AM series, to broaden application in diverse vehicle components.
3. How do sustainability, ESG, and environmental impact factors affect the Automotive Magnesium Alloy market?
Magnesium alloys contribute to automotive sustainability by significantly reducing vehicle weight, which in turn improves fuel economy and lowers CO2 emissions. The recyclability of magnesium also positions it favorably in the circular economy, aligning with stringent environmental, social, and governance (ESG) objectives for automotive manufacturers globally.
4. What is the current market size, valuation, and CAGR projection for Automotive Magnesium Alloy through 2033?
The Automotive Magnesium Alloy market was valued at $4.3 billion in 2023. This market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.1% from 2023 through 2033. This growth reflects sustained demand for lightweight solutions across various automotive applications.
5. Which export-import dynamics and international trade flows impact the Automotive Magnesium Alloy market?
International trade flows for automotive magnesium alloys are primarily driven by the global supply chains of major automotive OEMs and component manufacturers. Countries with significant magnesium production, like China (Yinguang Magnesium Industry, DongGuan Eontec), export raw alloys and semi-finished components to automotive manufacturing hubs in Europe and North America.
6. What is the regulatory environment and compliance impact on the Automotive Magnesium Alloy market?
The regulatory environment, particularly stringent emissions standards and fuel economy mandates, heavily influences the Automotive Magnesium Alloy market. Regulations across regions compel automakers to adopt lightweight materials, increasing demand for magnesium alloys to meet compliance targets. This regulatory push accelerates the integration of magnesium into structural body components and engine cradles.