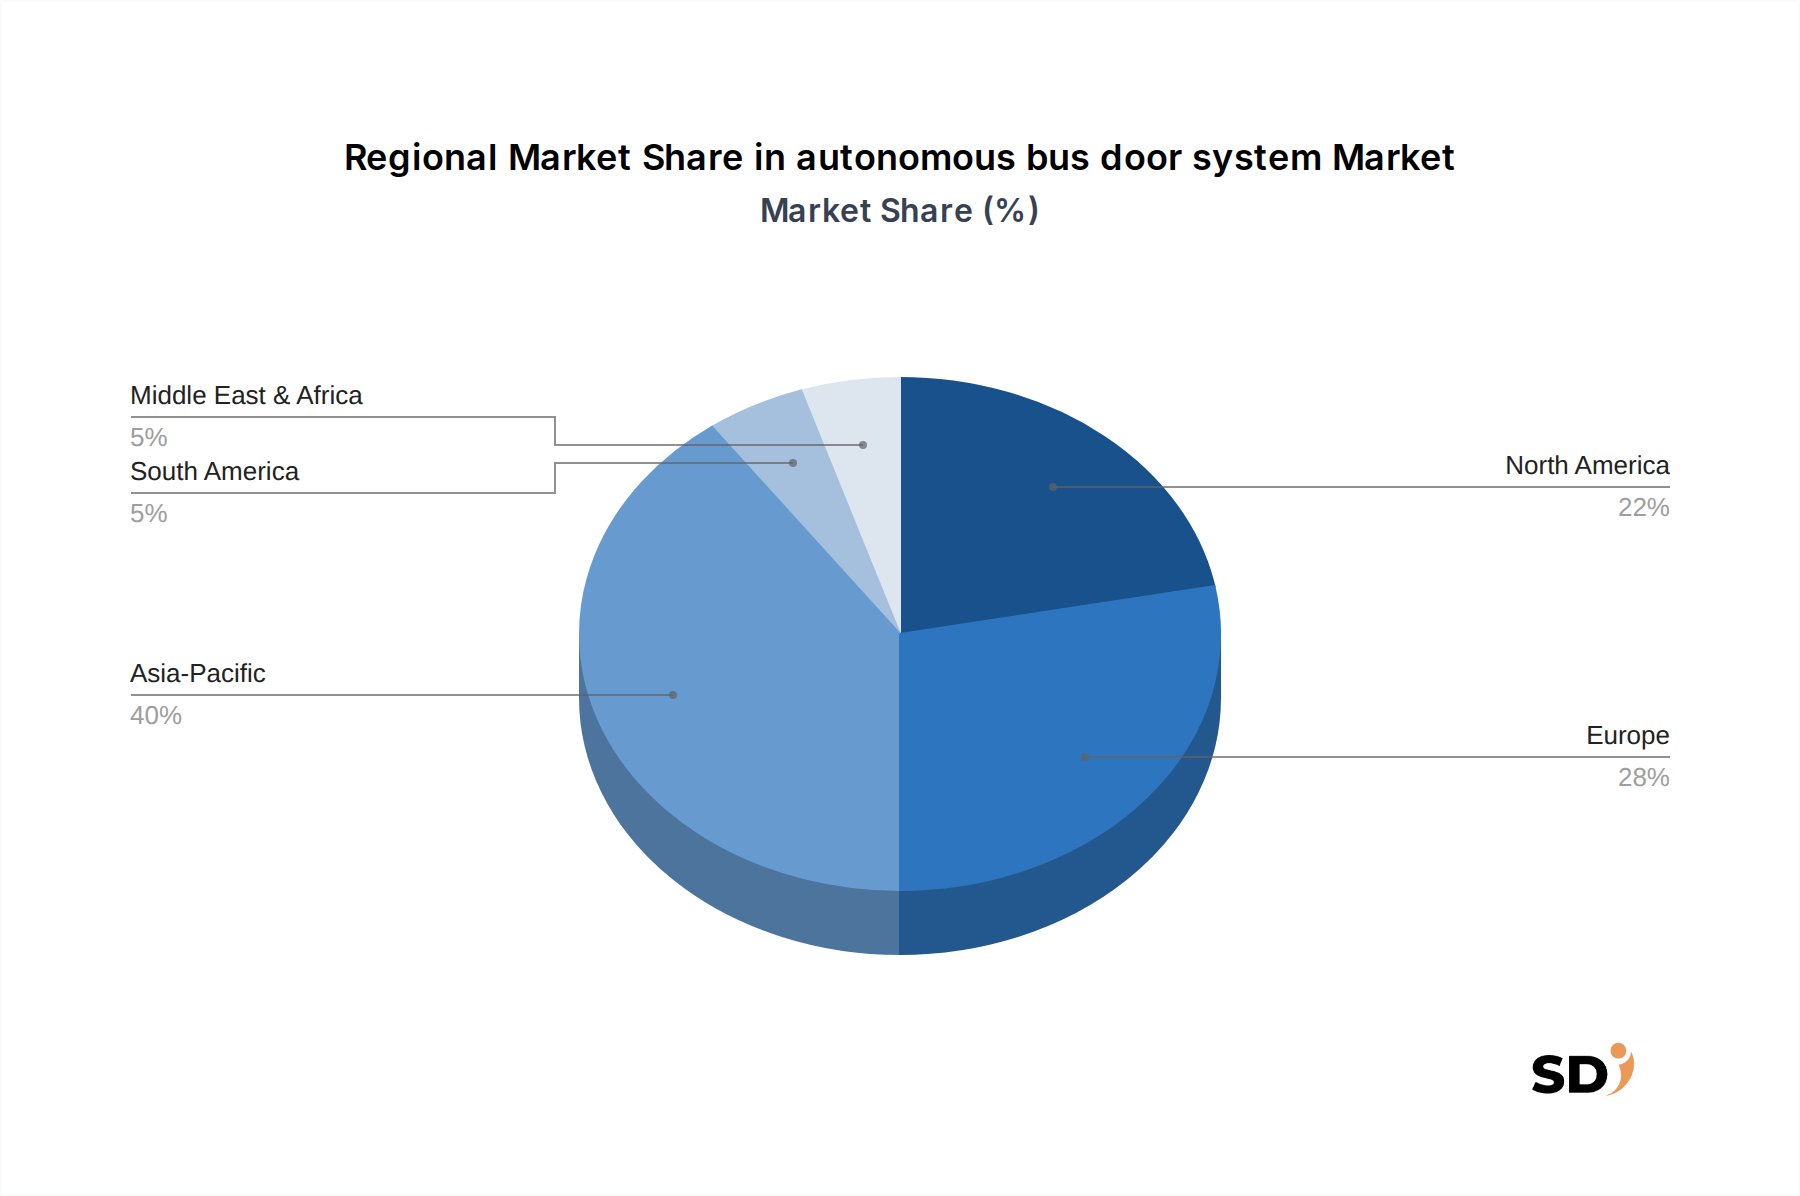
The autonomous bus door system Market is subject to complex international trade dynamics, influenced by cross-border component flows, regional manufacturing hubs, and evolving tariff and non-tariff barriers.
Major Trade Corridors: Critical components, such as advanced sensors and microcontrollers for the Autonomous Vehicle Sensor Market, often flow from East Asia (e.g., Japan, South Korea, Taiwan, China) to assembly plants in Europe and North America. Conversely, specialized high-precision actuators and control units may originate from Europe, then exported globally. Intra-Asian trade is significant for volume components and complete door system sub-assemblies due to the region's robust manufacturing capabilities and growing Electric Bus Market.
Leading Exporting Nations: Germany is a key exporter of high-precision mechanical and electronic components, including sophisticated actuators and control units, leveraging its strong engineering base. Japan and South Korea are prominent for advanced sensor technologies (LiDAR, radar) and high-quality electronic components. China dominates as a leading exporter of cost-effective components and complete door system modules, particularly for high-volume markets, playing a crucial role in the global supply chain for the autonomous bus door system Market.
Leading Importing Nations: Countries with ambitious smart city development plans and significant investments in public transportation automation, such as the United Arab Emirates (UAE), Saudi Arabia, and select nations in Southeast Asia, are major importers of advanced autonomous bus door systems. Additionally, countries with burgeoning bus manufacturing industries like India and Brazil import specialized components to integrate into their domestic vehicle production. Developed markets in Europe and North America also import niche technologies and components to complement their local manufacturing capabilities for the Public Transportation Automation Market.
Tariff Impact: Historical trade tensions, such as the US-China trade war (2018-2019), led to the imposition of tariffs ranging from 15-25% on various automotive components, including electronics and mechanical parts essential for door systems. These tariffs increased the landed cost for manufacturers sourcing from affected regions, prompting shifts in supply chain strategies and impacting the overall pricing structure within the autonomous bus door system Market. While some tariffs have been adjusted, the underlying risk of protectionist trade policies continues to influence sourcing decisions and market accessibility for the Automotive Safety Systems Market.
Non-Tariff Barriers: Beyond tariffs, non-tariff barriers (NTBs) significantly impact cross-border trade. These include stringent regional technical standards and certification requirements (e.g., EU safety directives, UNECE regulations), which mandate extensive testing and compliance for autonomous door systems. Local content requirements, often imposed by governments to foster domestic industries, can also act as barriers, necessitating local manufacturing or assembly partnerships. These NTBs add complexity and cost to market entry, influencing global trade flows and component choices for the autonomous bus door system Market.