Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Bacterial ID & DST Market: $25.83B by 2033, 7.6% CAGR
Bacterial Identification and Drug Sensitivity Testing
Bacterial ID & DST Market: $25.83B by 2033, 7.6% CAGR
Bacterial Identification and Drug Sensitivity Testing by Product Type (Instruments, Consumables, Reagents & Kits, Others), by Testing Method (Automated Testing, Manual Testing), by Technology (Polymerase Chain Reaction (PCR), Mass Spectrometry, Microarray, Next-Generation Sequencing (NGS), Immunoassays, Flow Cytometry, Others), by Application (Clinical Diagnostics, Drug Discovery & Development, Infection Control & Surveillance, Veterinary Diagnostics, Food Safety Testing, Environmental Testing, Others), by End User (Hospitals, Diagnostic Laboratories, Academic & Research Institutes, Pharmaceutical & Biotechnology Companies, Veterinary Clinics & Laboratories, Food Testing Laboratories), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 2, 2026|Base Year : 2025|Pages : 91
Key Insights for the Bacterial Identification and Drug Sensitivity Testing Market
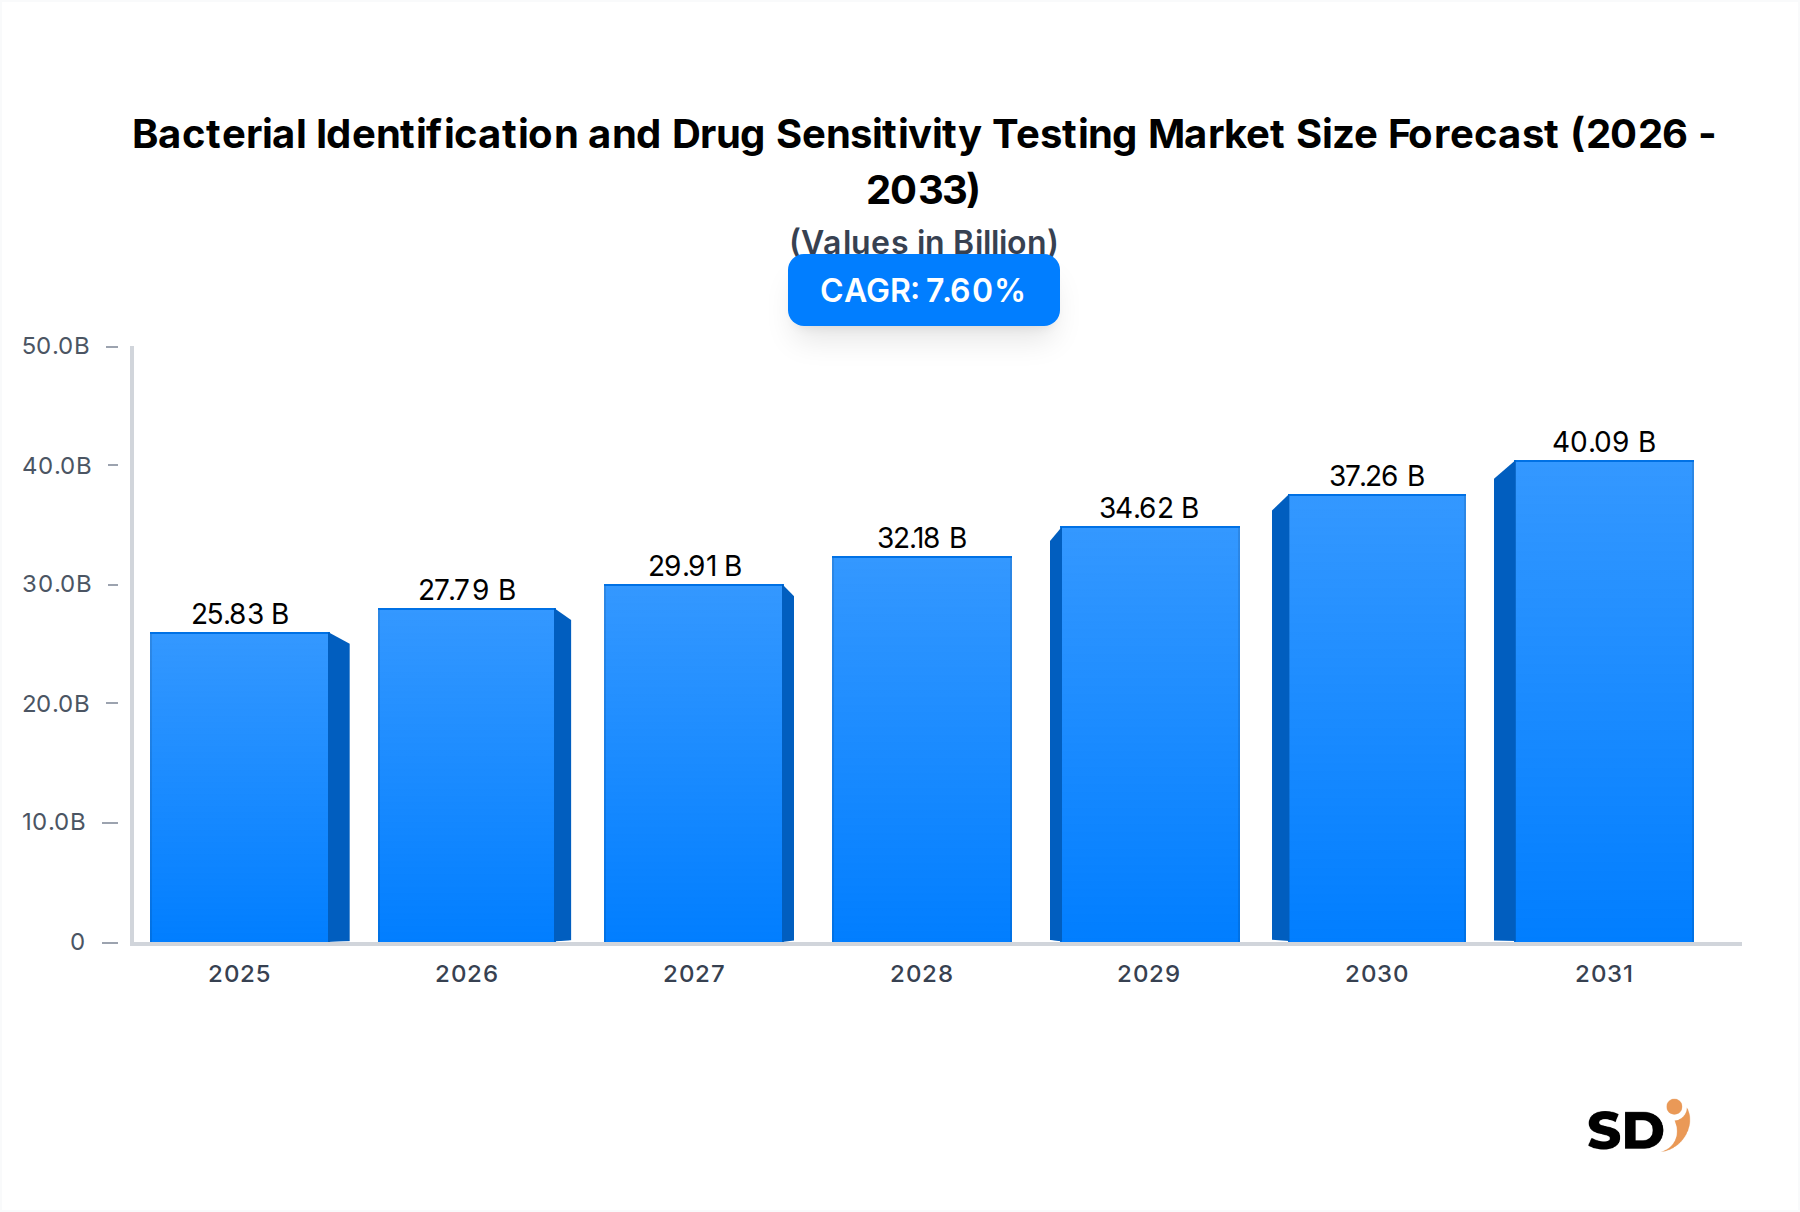
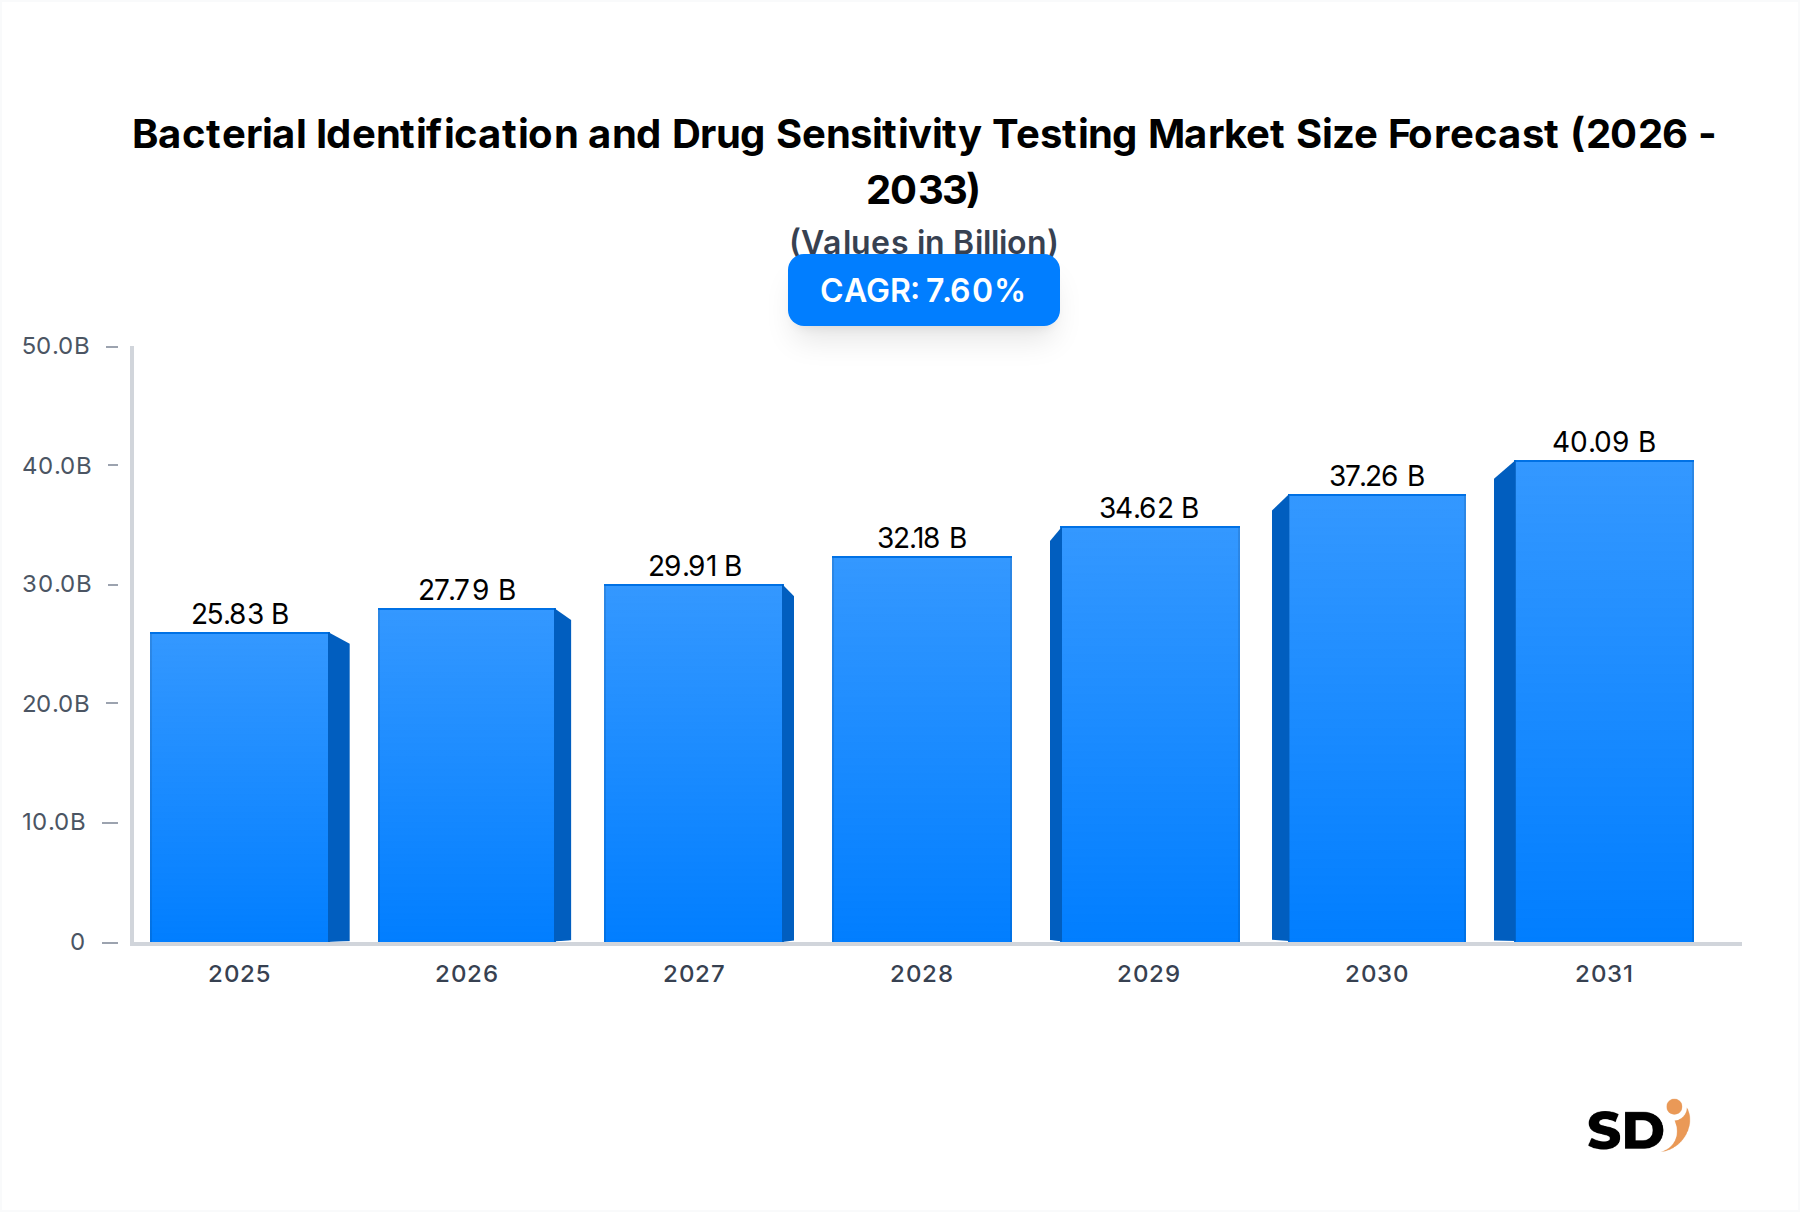
The global Bacterial Identification and Drug Sensitivity Testing Market is poised for substantial expansion, demonstrating the critical need for precise and timely pathogen detection and antimicrobial susceptibility determination. Valued at an estimated $25.83 billion in 2025, the market is projected to reach approximately $46.55 billion by 2033, advancing at an impressive Compound Annual Growth Rate (CAGR) of 7.6% over the forecast period. This robust growth trajectory is underpinned by several pervasive demand drivers. A primary catalyst is the escalating global burden of infectious diseases, compounded by the dire challenge of antimicrobial resistance (AMR), which necessitates rapid and accurate diagnostic solutions to guide effective therapeutic interventions. Technological advancements, particularly in areas such as mass spectrometry, next-generation sequencing (NGS), and advanced polymerase chain reaction (PCR) platforms, are revolutionizing the speed and precision of bacterial identification and drug sensitivity testing. These innovations enable earlier detection and more targeted treatment, curbing the spread of resistant strains and improving patient outcomes. Furthermore, increasing healthcare expenditure, expanding diagnostic infrastructure, especially in emerging economies, and a growing emphasis on infection control and surveillance programs significantly bolster market demand. The demand for efficient and high-throughput diagnostic solutions is also driving the Laboratory Automation Market, directly impacting how bacterial identification and drug sensitivity testing is performed. The market's forward-looking outlook indicates a significant shift towards automated, multiplexed, and Point-of-Care Diagnostics Market solutions, offering rapid results closer to the patient. The ongoing integration of these diagnostics with digital health platforms and the broader In Vitro Diagnostics Market is set to enhance data management, epidemiological surveillance, and overall public health responses, solidifying the market's indispensable role in modern healthcare. Growth in the Molecular Diagnostics Market also plays a crucial role in enabling faster, more accurate identification of pathogens and resistance genes.
Bacterial Identification and Drug Sensitivity Testing Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
25.83 B
2025
27.79 B
2026
29.91 B
2027
32.18 B
2028
34.62 B
2029
37.26 B
2030
40.09 B
2031
Clinical Diagnostics Segment Dominance in Bacterial Identification and Drug Sensitivity Testing Market
The Clinical Diagnostics segment undeniably holds the largest revenue share within the Bacterial Identification and Drug Sensitivity Testing Market, driven by its direct and critical impact on patient care and public health. This segment encompasses all diagnostic activities performed in hospitals, reference laboratories, and other clinical settings to identify pathogenic bacteria and determine their susceptibility to various antimicrobial agents. The dominance of clinical diagnostics stems from the sheer volume of tests performed daily globally, addressing a wide spectrum of bacterial infections ranging from routine urinary tract infections to life-threatening sepsis. The rapid and accurate output from these tests is paramount for clinicians to initiate appropriate treatment regimens, prevent the spread of infections, and mitigate the development of antimicrobial resistance. The imperative to manage hospital-acquired infections (HAIs) and healthcare-associated infections (HAIs) further solidifies the segment's leading position, as robust bacterial identification and drug sensitivity testing are foundational to effective infection control programs. Major players like BioMerieux, Becton, Dickinson and Company, and F. Hoffmann-La Roche Ltd, among others, have significant portfolios tailored to the demanding requirements of clinical laboratories, offering a comprehensive suite of instruments, Diagnostic Reagents Market, and consumables. The ongoing evolution within the Infectious Disease Diagnostics Market is heavily influenced by advancements driven by clinical needs, such as the development of multiplex PCR panels for rapid syndromic testing and the integration of mass spectrometry for quicker species identification. Moreover, the increasing adoption of automated systems for high-throughput processing is streamlining workflows in busy Clinical Microbiology Market laboratories, enhancing efficiency and reducing turnaround times. The continuous demand for diagnostics that can cope with emerging pathogens and evolving resistance patterns ensures that the Clinical Diagnostics segment will not only maintain its leading share but also continue to be the primary driver for innovation and investment across the entire Bacterial Identification and Drug Sensitivity Testing Market. The focus remains on improving the sensitivity, specificity, and speed of tests to deliver actionable results that directly improve patient outcomes and global health security.
Critical Drivers Fueling the Bacterial Identification and Drug Sensitivity Testing Market
The Bacterial Identification and Drug Sensitivity Testing Market is propelled by a confluence of critical drivers, each contributing significantly to its expansion and technological evolution. One of the foremost drivers is the escalating Antimicrobial Resistance (AMR) Crisis. The World Health Organization (WHO) has highlighted AMR as a top 10 global public health threat, estimating that over 1.27 million deaths globally in 2019 were directly attributable to drug-resistant bacterial infections. This alarming statistic underscores the urgent need for rapid and accurate drug sensitivity testing to guide targeted antibiotic therapy, thereby preserving the efficacy of existing drugs and informing the development of new ones. Consequently, the demand for sophisticated diagnostic tools that can quickly identify resistant strains is intensifying across all healthcare settings. Another significant impetus is the Rising Burden of Infectious Diseases worldwide. Despite advances in public health, bacterial infections continue to impose a substantial disease burden, particularly in low- and middle-income countries. Reports from global health bodies consistently indicate a high prevalence of bacterial respiratory infections, bloodstream infections, and gastrointestinal diseases, which directly fuels the demand for the broader Infectious Disease Diagnostics Market. The continuous emergence of new pathogens and re-emergence of existing ones also necessitates constant innovation in bacterial identification methods. Technological Advancements represent a pivotal driver. The development and commercialization of cutting-edge technologies, such as MALDI-TOF mass spectrometry for rapid bacterial identification, advanced nucleic acid amplification techniques (e.g., real-time PCR), and the increasing application of the Next-Generation Sequencing Market for comprehensive genomic analysis of pathogens, are transforming the diagnostic landscape. These technologies offer faster turnaround times, higher accuracy, and the ability to detect multiple pathogens and resistance genes simultaneously, making them indispensable in modern diagnostics. Furthermore, the growing adoption of Laboratory Automation Market solutions is enhancing throughput and efficiency in diagnostic laboratories. Automated systems reduce manual labor, minimize human error, and enable high-volume testing, which is crucial for managing large patient populations and epidemiological surveillance. Finally, Increased Healthcare Spending and Infrastructure Development, particularly in developing regions, are expanding access to advanced diagnostic services. Governments and private entities are investing in establishing modern diagnostic laboratories and upgrading existing facilities, thereby increasing the reach and utilization of bacterial identification and drug sensitivity testing, which includes a steady demand for Diagnostic Reagents Market and related consumables.
Competitive Ecosystem of Bacterial Identification and Drug Sensitivity Testing Market
Within the Bacterial Identification and Drug Sensitivity Testing Market, competition is intense, driven by continuous innovation in diagnostic technologies and the urgent global need to combat infectious diseases and antimicrobial resistance. Key players leverage extensive R&D, strategic partnerships, and broad product portfolios to maintain and expand their market presence:
BioMerieux: A leading global player in in vitro diagnostics, with a strong focus on microbiology solutions, offering a comprehensive range of automated systems, reagents, and software for bacterial identification and antimicrobial susceptibility testing.
Becton, Dickinson and Company: Known for its extensive range of medical technology, BD is a significant force in diagnostics, providing integrated solutions for microbiology laboratories, including automated platforms for pathogen identification and susceptibility testing.
Danaher Corporation: Through its various life science and diagnostics operating companies, Danaher offers a diverse portfolio of products and services that contribute to the bacterial identification and drug sensitivity testing space, particularly in molecular diagnostics.
Thermo Fisher Scientific: A global leader in scientific instrumentation, consumables, and software, Thermo Fisher provides a wide array of products applicable to microbiology diagnostics, from sample preparation to mass spectrometry-based identification.
Bruker Corporation: A key innovator in the market, Bruker is particularly renowned for its MALDI Biotyper system, which utilizes mass spectrometry for rapid and highly accurate microbial identification, significantly impacting clinical workflows.
F. Hoffmann-La Roche Ltd: A multinational healthcare company with a strong diagnostics division, Roche offers a broad range of molecular diagnostic solutions and automated laboratory systems, including those relevant for infectious disease testing.
Abbott Laboratories: With a comprehensive diagnostics portfolio, Abbott provides solutions for infectious disease testing, including molecular and rapid diagnostic platforms that aid in bacterial identification and detection of resistance markers.
QIAGEN N.V.: A prominent provider of sample and assay technologies for Molecular Diagnostics Market, QIAGEN offers various kits and instruments essential for nucleic acid-based bacterial identification and characterization.
Bio-Rad Laboratories: Offers a diverse range of products for the life science research and clinical diagnostics markets, including instruments and reagents used in Clinical Microbiology Market and infectious disease testing.
Sysmex Corporation: While traditionally strong in hematology and urinalysis, Sysmex is expanding its diagnostic offerings, contributing to the broader laboratory diagnostics ecosystem with solutions that support infectious disease management.
Recent Developments & Milestones in Bacterial Identification and Drug Sensitivity Testing Market
The Bacterial Identification and Drug Sensitivity Testing Market is characterized by continuous innovation and strategic advancements aimed at improving diagnostic accuracy, speed, and accessibility. Recent milestones reflect a concerted effort to address the challenges posed by evolving pathogens and antimicrobial resistance:
February 2025: Introduction of a novel AI-powered algorithm for enhanced susceptibility prediction from phenotypic data, reducing manual interpretation time by 30% and improving consistency across laboratories.
September 2024: Launch of a fully automated pathogen identification and antimicrobial susceptibility testing (AST) system capable of processing 500 samples per shift, significantly boosting Laboratory Automation Market capabilities in high-volume diagnostic centers.
June 2024: Strategic partnership between a leading diagnostics firm and a biotechnology startup to integrate CRISPR-based detection for rapid, multiplexed bacterial identification, targeting specific resistant strains with unprecedented precision.
March 2024: Regulatory approval in the EU for a new Point-of-Care Diagnostics Market device offering rapid identification of common respiratory bacterial pathogens and key resistance markers within 30 minutes, facilitating faster clinical decisions.
November 2023: Investment of $150 million by a major pharmaceutical company into a research initiative focused on novel phenotypic AST methods for difficult-to-treat infections, emphasizing the critical role of diagnostics in drug discovery.
August 2023: Publication of clinical validation data demonstrating the superior accuracy of a new Next-Generation Sequencing Market based assay for complex polymicrobial infection analysis compared to traditional culture-based methods, opening new avenues for personalized medicine.
Geographical Performance: Regional Market Breakdown for Bacterial Identification and Drug Sensitivity Testing Market
The global Bacterial Identification and Drug Sensitivity Testing Market exhibits significant regional variations in terms of maturity, growth drivers, and market penetration. A detailed analysis across key geographies reveals distinct dynamics:
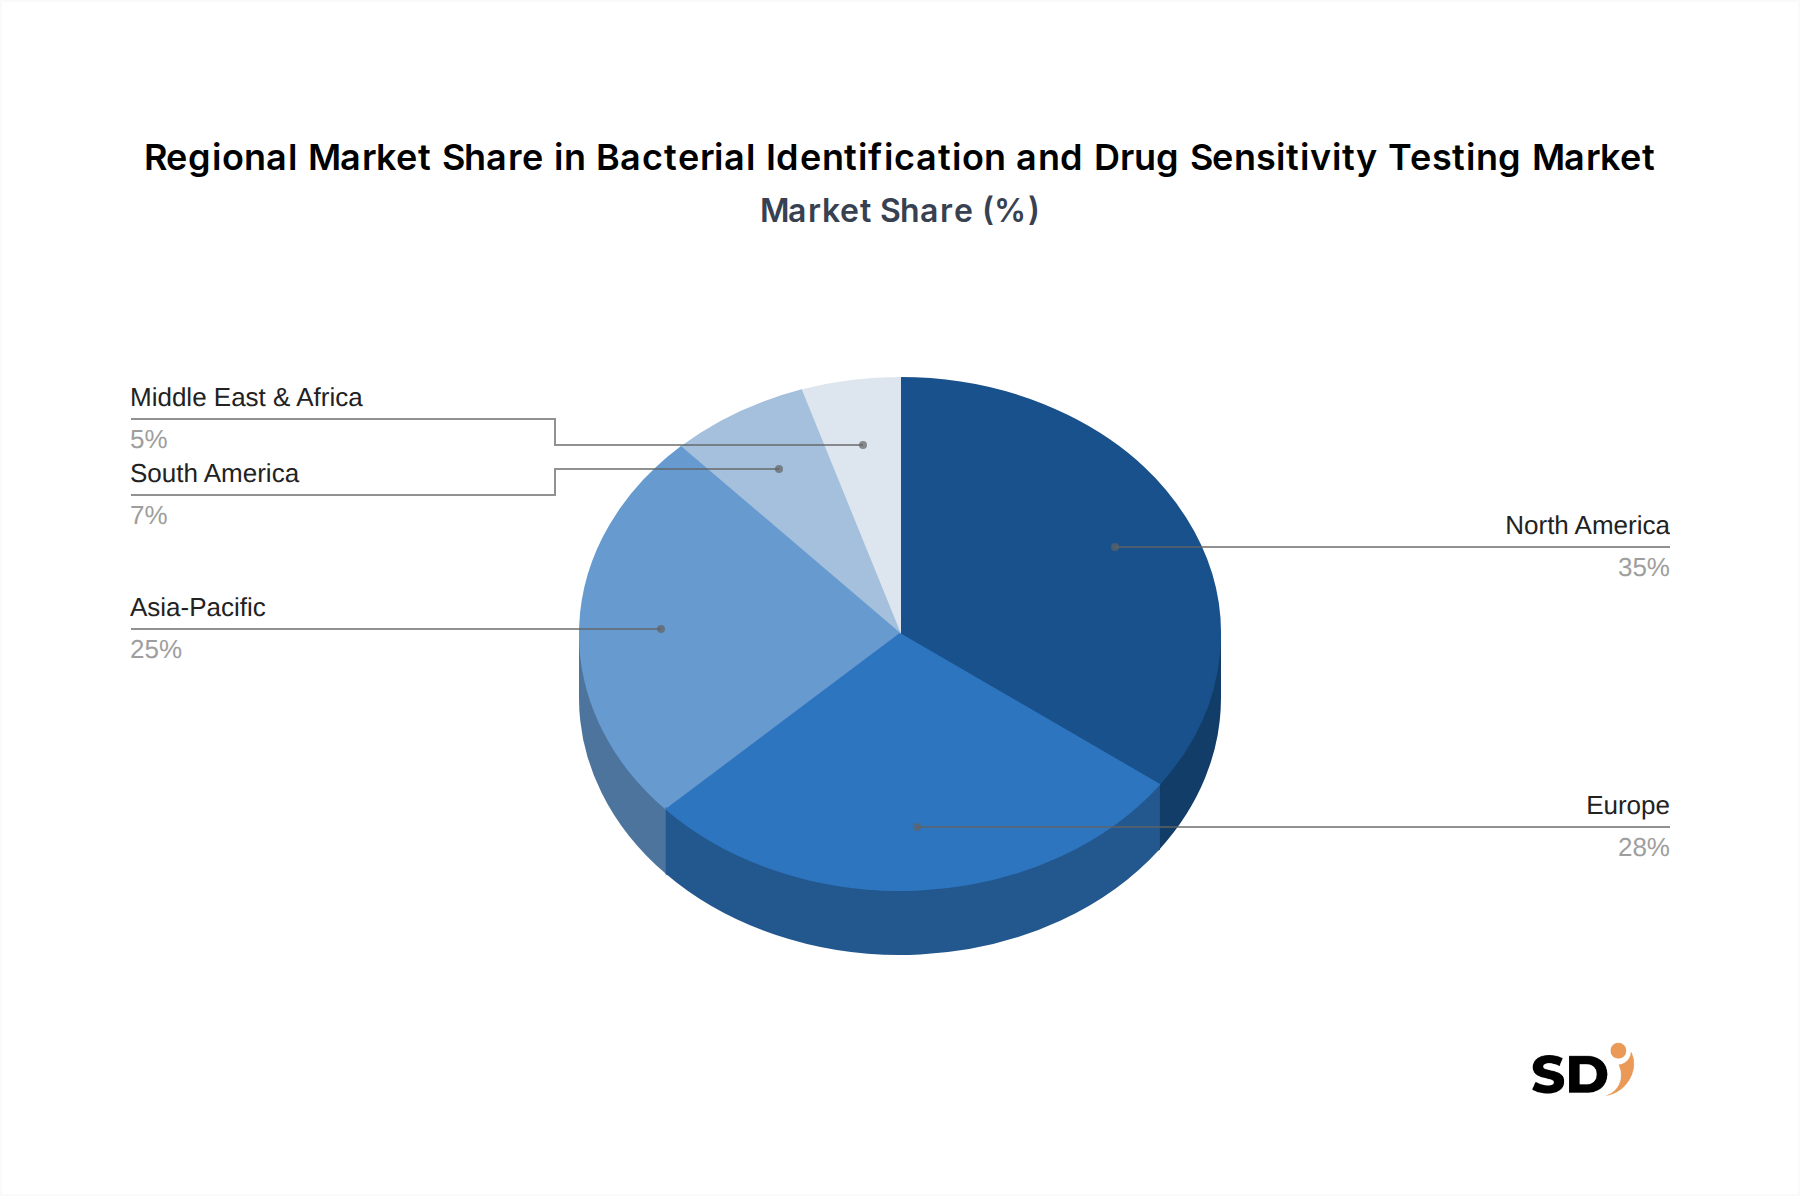
North America: This region holds the largest share of the market, estimated at approximately 38% in 2025, primarily due to high healthcare expenditure, advanced healthcare infrastructure, and early adoption of cutting-edge diagnostic technologies. The presence of key market players and a robust focus on AMR surveillance programs further solidify its position. The region is expected to grow at a steady CAGR of 6.8%, reflecting a mature but continuously innovating market. The strong regulatory framework and reimbursement policies also encourage the uptake of sophisticated diagnostic tools within the In Vitro Diagnostics Market.
Europe: Representing a substantial market share of around 29%, Europe is a significant contributor to the global Bacterial Identification and Drug Sensitivity Testing Market. Growth is driven by an aging population, rising prevalence of infectious diseases, strong research & development activities, and a well-established healthcare system. The European market is projected to expand at a CAGR of 7.2%, influenced by stringent regulatory mandates such as the In Vitro Diagnostic Regulation (IVDR), which pushes for higher standards in product quality and clinical performance. The demand for advanced Diagnostic Reagents Market and instruments remains consistently high.
Asia Pacific: This region is identified as the fastest-growing market, with a projected CAGR of 9.5% over the forecast period. Accounting for roughly 22% of the global market in 2025, its expansion is fueled by rapidly improving healthcare infrastructure, increasing healthcare accessibility, a large and growing population base, and a high burden of infectious diseases. Countries like China, India, and Japan are making significant investments in their Clinical Microbiology Market capabilities, driving demand for both automated and traditional testing methods.
Latin America: An emerging market demonstrating promising growth, Latin America is expected to contribute approximately 6% to the global market, with an estimated CAGR of 8.1%. The region's growth is primarily attributed to increasing awareness about infectious diseases, improvements in public health initiatives, and a gradual enhancement of diagnostic laboratory capabilities. There's a growing appetite for cost-effective and efficient diagnostic solutions to address prevalent local health challenges.
Middle East & Africa: While currently holding a smaller share, this region is witnessing substantial growth potential with an estimated CAGR of 7.9%. Investments in healthcare infrastructure, driven by government initiatives and increasing medical tourism in some parts, are opening new avenues for the adoption of bacterial identification and drug sensitivity testing, particularly in the GCC countries and South Africa.
Sustainability & ESG Pressures on Bacterial Identification and Drug Sensitivity Testing Market
The Bacterial Identification and Drug Sensitivity Testing Market is increasingly influenced by global sustainability trends and Environmental, Social, and Governance (ESG) criteria. Laboratories and manufacturers are facing mounting pressure to adopt more environmentally friendly practices and demonstrate social responsibility. A key area of focus is waste reduction, particularly concerning the high volume of single-use plastics and chemical reagents used in diagnostic procedures. This drives innovation towards developing reusable components, recyclable packaging for Diagnostic Reagents Market and consumables, and exploring biodegradable materials. Energy efficiency in laboratory instrumentation is another critical aspect, with a push for analyzers and automated systems in the Laboratory Automation Market that consume less power and generate less heat, thereby reducing the carbon footprint of diagnostic facilities. Manufacturers are also under scrutiny for their supply chain ethics, ensuring responsible sourcing of raw materials and fair labor practices. From a social perspective, the affordability and accessibility of bacterial identification and drug sensitivity testing, especially in low-resource settings, are paramount. Companies are increasingly evaluated on their efforts to provide diagnostics that are both effective and equitable. ESG investors are actively scrutinizing companies' environmental impact, waste management policies, and social contributions, pushing market players to integrate sustainability into their core business strategies. This includes designing instruments with longer lifecycles, offering refurbishment programs, and adhering to circular economy principles to minimize waste and maximize resource utility across the entire product lifecycle.
Regulatory & Policy Landscape Shaping Bacterial Identification and Drug Sensitivity Testing Market
The Bacterial Identification and Drug Sensitivity Testing Market operates within a complex and continuously evolving regulatory and policy landscape across key geographies. These frameworks are critical for ensuring the safety, efficacy, and quality of diagnostic products. In the United States, the Food and Drug Administration (FDA) plays a central role in approving new diagnostic devices and assays, including those leveraging advanced technologies like Next-Generation Sequencing Market for pathogen identification. The Clinical Laboratory Improvement Amendments (CLIA) further establish quality standards for all laboratory testing performed on human samples in the US, regardless of where the tests are performed. In the European Union, the In Vitro Diagnostic Regulation (IVDR), which became fully applicable in May 2022, has significantly reshaped the market. IVDR mandates more rigorous clinical evidence, stricter conformity assessments, and enhanced post-market surveillance for all in vitro diagnostic medical devices, including bacterial identification and drug sensitivity tests. This has implications for product development cycles, market entry, and compliance costs for manufacturers. Global organizations such as the World Health Organization (WHO) also influence the market through guidelines on antimicrobial resistance (AMR) surveillance, standardization of diagnostic methods, and recommendations for Point-of-Care Diagnostics Market in resource-limited settings. ISO standards, such as ISO 15189 for medical laboratories, provide a framework for quality and competence, further shaping laboratory practices. Recent policy shifts, particularly those aimed at combating AMR, often prioritize rapid diagnostics and surveillance, creating incentives for innovation and adoption of new testing platforms. These policies can significantly impact market dynamics by accelerating the approval of novel technologies, influencing reimbursement structures, and driving procurement trends towards solutions that offer faster, more accurate, and comprehensive diagnostic capabilities.
Bacterial Identification and Drug Sensitivity Testing Segmentation
1. Product Type
1.1. Instruments
1.2. Consumables
1.3. Reagents & Kits
1.4. Others
2. Testing Method
2.1. Automated Testing
2.2. Manual Testing
3. Technology
3.1. Polymerase Chain Reaction (PCR)
3.2. Mass Spectrometry
3.3. Microarray
3.4. Next-Generation Sequencing (NGS)
3.5. Immunoassays
3.6. Flow Cytometry
3.7. Others
4. Application
4.1. Clinical Diagnostics
4.2. Drug Discovery & Development
4.3. Infection Control & Surveillance
4.4. Veterinary Diagnostics
4.5. Food Safety Testing
4.6. Environmental Testing
4.7. Others
5. End User
5.1. Hospitals
5.2. Diagnostic Laboratories
5.3. Academic & Research Institutes
5.4. Pharmaceutical & Biotechnology Companies
5.5. Veterinary Clinics & Laboratories
5.6. Food Testing Laboratories
Bacterial Identification and Drug Sensitivity Testing Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Bacterial Identification and Drug Sensitivity Testing REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.6% from 2020-2034
Segmentation
By Product Type
Instruments
Consumables
Reagents & Kits
Others
By Testing Method
Automated Testing
Manual Testing
By Technology
Polymerase Chain Reaction (PCR)
Mass Spectrometry
Microarray
Next-Generation Sequencing (NGS)
Immunoassays
Flow Cytometry
Others
By Application
Clinical Diagnostics
Drug Discovery & Development
Infection Control & Surveillance
Veterinary Diagnostics
Food Safety Testing
Environmental Testing
Others
By End User
Hospitals
Diagnostic Laboratories
Academic & Research Institutes
Pharmaceutical & Biotechnology Companies
Veterinary Clinics & Laboratories
Food Testing Laboratories
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Instruments
5.1.2. Consumables
5.1.3. Reagents & Kits
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Testing Method
5.2.1. Automated Testing
5.2.2. Manual Testing
5.3. Market Analysis, Insights and Forecast - by Technology
5.3.1. Polymerase Chain Reaction (PCR)
5.3.2. Mass Spectrometry
5.3.3. Microarray
5.3.4. Next-Generation Sequencing (NGS)
5.3.5. Immunoassays
5.3.6. Flow Cytometry
5.3.7. Others
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Clinical Diagnostics
5.4.2. Drug Discovery & Development
5.4.3. Infection Control & Surveillance
5.4.4. Veterinary Diagnostics
5.4.5. Food Safety Testing
5.4.6. Environmental Testing
5.4.7. Others
5.5. Market Analysis, Insights and Forecast - by End User
5.5.1. Hospitals
5.5.2. Diagnostic Laboratories
5.5.3. Academic & Research Institutes
5.5.4. Pharmaceutical & Biotechnology Companies
5.5.5. Veterinary Clinics & Laboratories
5.5.6. Food Testing Laboratories
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. South America
5.6.3. Europe
5.6.4. Middle East & Africa
5.6.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Instruments
6.1.2. Consumables
6.1.3. Reagents & Kits
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Testing Method
6.2.1. Automated Testing
6.2.2. Manual Testing
6.3. Market Analysis, Insights and Forecast - by Technology
6.3.1. Polymerase Chain Reaction (PCR)
6.3.2. Mass Spectrometry
6.3.3. Microarray
6.3.4. Next-Generation Sequencing (NGS)
6.3.5. Immunoassays
6.3.6. Flow Cytometry
6.3.7. Others
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Clinical Diagnostics
6.4.2. Drug Discovery & Development
6.4.3. Infection Control & Surveillance
6.4.4. Veterinary Diagnostics
6.4.5. Food Safety Testing
6.4.6. Environmental Testing
6.4.7. Others
6.5. Market Analysis, Insights and Forecast - by End User
6.5.1. Hospitals
6.5.2. Diagnostic Laboratories
6.5.3. Academic & Research Institutes
6.5.4. Pharmaceutical & Biotechnology Companies
6.5.5. Veterinary Clinics & Laboratories
6.5.6. Food Testing Laboratories
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Instruments
7.1.2. Consumables
7.1.3. Reagents & Kits
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Testing Method
7.2.1. Automated Testing
7.2.2. Manual Testing
7.3. Market Analysis, Insights and Forecast - by Technology
7.3.1. Polymerase Chain Reaction (PCR)
7.3.2. Mass Spectrometry
7.3.3. Microarray
7.3.4. Next-Generation Sequencing (NGS)
7.3.5. Immunoassays
7.3.6. Flow Cytometry
7.3.7. Others
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Clinical Diagnostics
7.4.2. Drug Discovery & Development
7.4.3. Infection Control & Surveillance
7.4.4. Veterinary Diagnostics
7.4.5. Food Safety Testing
7.4.6. Environmental Testing
7.4.7. Others
7.5. Market Analysis, Insights and Forecast - by End User
7.5.1. Hospitals
7.5.2. Diagnostic Laboratories
7.5.3. Academic & Research Institutes
7.5.4. Pharmaceutical & Biotechnology Companies
7.5.5. Veterinary Clinics & Laboratories
7.5.6. Food Testing Laboratories
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Instruments
8.1.2. Consumables
8.1.3. Reagents & Kits
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Testing Method
8.2.1. Automated Testing
8.2.2. Manual Testing
8.3. Market Analysis, Insights and Forecast - by Technology
8.3.1. Polymerase Chain Reaction (PCR)
8.3.2. Mass Spectrometry
8.3.3. Microarray
8.3.4. Next-Generation Sequencing (NGS)
8.3.5. Immunoassays
8.3.6. Flow Cytometry
8.3.7. Others
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Clinical Diagnostics
8.4.2. Drug Discovery & Development
8.4.3. Infection Control & Surveillance
8.4.4. Veterinary Diagnostics
8.4.5. Food Safety Testing
8.4.6. Environmental Testing
8.4.7. Others
8.5. Market Analysis, Insights and Forecast - by End User
8.5.1. Hospitals
8.5.2. Diagnostic Laboratories
8.5.3. Academic & Research Institutes
8.5.4. Pharmaceutical & Biotechnology Companies
8.5.5. Veterinary Clinics & Laboratories
8.5.6. Food Testing Laboratories
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Instruments
9.1.2. Consumables
9.1.3. Reagents & Kits
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Testing Method
9.2.1. Automated Testing
9.2.2. Manual Testing
9.3. Market Analysis, Insights and Forecast - by Technology
9.3.1. Polymerase Chain Reaction (PCR)
9.3.2. Mass Spectrometry
9.3.3. Microarray
9.3.4. Next-Generation Sequencing (NGS)
9.3.5. Immunoassays
9.3.6. Flow Cytometry
9.3.7. Others
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Clinical Diagnostics
9.4.2. Drug Discovery & Development
9.4.3. Infection Control & Surveillance
9.4.4. Veterinary Diagnostics
9.4.5. Food Safety Testing
9.4.6. Environmental Testing
9.4.7. Others
9.5. Market Analysis, Insights and Forecast - by End User
9.5.1. Hospitals
9.5.2. Diagnostic Laboratories
9.5.3. Academic & Research Institutes
9.5.4. Pharmaceutical & Biotechnology Companies
9.5.5. Veterinary Clinics & Laboratories
9.5.6. Food Testing Laboratories
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Instruments
10.1.2. Consumables
10.1.3. Reagents & Kits
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Testing Method
10.2.1. Automated Testing
10.2.2. Manual Testing
10.3. Market Analysis, Insights and Forecast - by Technology
10.3.1. Polymerase Chain Reaction (PCR)
10.3.2. Mass Spectrometry
10.3.3. Microarray
10.3.4. Next-Generation Sequencing (NGS)
10.3.5. Immunoassays
10.3.6. Flow Cytometry
10.3.7. Others
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Clinical Diagnostics
10.4.2. Drug Discovery & Development
10.4.3. Infection Control & Surveillance
10.4.4. Veterinary Diagnostics
10.4.5. Food Safety Testing
10.4.6. Environmental Testing
10.4.7. Others
10.5. Market Analysis, Insights and Forecast - by End User
10.5.1. Hospitals
10.5.2. Diagnostic Laboratories
10.5.3. Academic & Research Institutes
10.5.4. Pharmaceutical & Biotechnology Companies
10.5.5. Veterinary Clinics & Laboratories
10.5.6. Food Testing Laboratories
11. Competitive Analysis
11.1. Company Profiles
11.1.1. BioMerieux
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Becton Dickinson and Company
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Danaher Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Thermo Fisher Scientific
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Bruker Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. F. Hoffmann-La Roche Ltd
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Abbott Laboratories
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. QIAGEN N.V.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Bio-Rad Laboratories
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Sysmex Corporation
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Others
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Bacterial Identification and Drug Sensitivity Testing Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Product Type 2026 & 2034
Figure 3: North America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Testing Method 2026 & 2034
Figure 5: North America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Testing Method 2026 & 2034
Figure 6: North America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Technology 2026 & 2034
Figure 7: North America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Application 2026 & 2034
Figure 9: North America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by End User 2026 & 2034
Figure 11: North America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by End User 2026 & 2034
Figure 12: North America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Country 2026 & 2034
Figure 13: North America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Country 2026 & 2034
Figure 14: South America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Product Type 2026 & 2034
Figure 15: South America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Product Type 2026 & 2034
Figure 16: South America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Testing Method 2026 & 2034
Figure 17: South America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Testing Method 2026 & 2034
Figure 18: South America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Technology 2026 & 2034
Figure 19: South America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Technology 2026 & 2034
Figure 20: South America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Application 2026 & 2034
Figure 21: South America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Application 2026 & 2034
Figure 22: South America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by End User 2026 & 2034
Figure 23: South America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by End User 2026 & 2034
Figure 24: South America Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Country 2026 & 2034
Figure 25: South America Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Country 2026 & 2034
Figure 26: Europe Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Product Type 2026 & 2034
Figure 27: Europe Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Europe Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Testing Method 2026 & 2034
Figure 29: Europe Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Testing Method 2026 & 2034
Figure 30: Europe Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Technology 2026 & 2034
Figure 31: Europe Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Technology 2026 & 2034
Figure 32: Europe Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Application 2026 & 2034
Figure 33: Europe Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Application 2026 & 2034
Figure 34: Europe Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by End User 2026 & 2034
Figure 35: Europe Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by End User 2026 & 2034
Figure 36: Europe Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Country 2026 & 2034
Figure 37: Europe Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Product Type 2026 & 2034
Figure 39: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Product Type 2026 & 2034
Figure 40: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Testing Method 2026 & 2034
Figure 41: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Testing Method 2026 & 2034
Figure 42: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Technology 2026 & 2034
Figure 43: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Technology 2026 & 2034
Figure 44: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Application 2026 & 2034
Figure 45: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Application 2026 & 2034
Figure 46: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by End User 2026 & 2034
Figure 47: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by End User 2026 & 2034
Figure 48: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Country 2026 & 2034
Figure 49: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Country 2026 & 2034
Figure 50: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Product Type 2026 & 2034
Figure 51: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Product Type 2026 & 2034
Figure 52: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Testing Method 2026 & 2034
Figure 53: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Testing Method 2026 & 2034
Figure 54: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Technology 2026 & 2034
Figure 55: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Technology 2026 & 2034
Figure 56: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Application 2026 & 2034
Figure 57: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Application 2026 & 2034
Figure 58: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by End User 2026 & 2034
Figure 59: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by End User 2026 & 2034
Figure 60: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue (billion), by Country 2026 & 2034
Figure 61: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Product Type 2020 & 2034
Table 2: Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Testing Method 2020 & 2034
Table 3: Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Technology 2020 & 2034
Table 4: Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Application 2020 & 2034
Table 5: Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by End User 2020 & 2034
Table 6: Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Region 2020 & 2034
Table 7: North America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Product Type 2020 & 2034
Table 8: North America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Testing Method 2020 & 2034
Table 9: North America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Technology 2020 & 2034
Table 10: North America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Application 2020 & 2034
Table 11: North America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by End User 2020 & 2034
Table 12: North America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Country 2020 & 2034
Table 13: United States Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 14: Canada Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: South America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Product Type 2020 & 2034
Table 17: South America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Testing Method 2020 & 2034
Table 18: South America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Technology 2020 & 2034
Table 19: South America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Application 2020 & 2034
Table 20: South America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by End User 2020 & 2034
Table 21: South America Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Country 2020 & 2034
Table 22: Brazil Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 23: Argentina Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Rest of South America Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: Europe Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Product Type 2020 & 2034
Table 26: Europe Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Testing Method 2020 & 2034
Table 27: Europe Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Technology 2020 & 2034
Table 28: Europe Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Application 2020 & 2034
Table 29: Europe Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by End User 2020 & 2034
Table 30: Europe Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Country 2020 & 2034
Table 31: United Kingdom Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Germany Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 33: France Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 34: Italy Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: Spain Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Russia Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Benelux Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: Nordics Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: Rest of Europe Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Product Type 2020 & 2034
Table 41: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Testing Method 2020 & 2034
Table 42: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Technology 2020 & 2034
Table 43: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Application 2020 & 2034
Table 44: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by End User 2020 & 2034
Table 45: Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Country 2020 & 2034
Table 46: Turkey Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: Israel Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: GCC Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: North Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: South Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Rest of Middle East & Africa Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Product Type 2020 & 2034
Table 53: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Testing Method 2020 & 2034
Table 54: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Technology 2020 & 2034
Table 55: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Application 2020 & 2034
Table 56: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by End User 2020 & 2034
Table 57: Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue billion Forecast, by Country 2020 & 2034
Table 58: China Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 59: India Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 60: Japan Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 61: South Korea Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 62: ASEAN Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 63: Oceania Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Table 64: Rest of Asia Pacific Bacterial Identification and Drug Sensitivity Testing Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our primary research phase constitutes the cornerstone of our market analysis, contributing an estimated 70-80% to the overall data and insights. This phase involves extensive qualitative and quantitative interviews with key opinion leaders (KOLs) and stakeholders across the bacterial identification and drug sensitivity testing value chain. Our interviews are meticulously structured to gather first-hand information on market dynamics, technological advancements, competitive landscape, pricing trends, regulatory impacts, and future growth prospects across various geographies.
Key stakeholders interviewed include:
Head of Clinical Microbiology/Laboratory Director: From hospitals and independent diagnostic laboratories, providing insights on testing volumes, technology adoption, and operational challenges.
VP/Director of Infectious Disease R&D: From pharmaceutical and biotechnology companies, offering perspectives on drug discovery needs, companion diagnostics, and research priorities.
Product Manager, Microbiology Diagnostics: From IVD instrument and reagent manufacturing companies, detailing product portfolios, market strategies, and competitive positioning.
Supply Chain/Procurement Manager, Laboratory Equipment: From major hospital networks or diagnostic chains, providing data on purchasing patterns, budget constraints, and vendor preferences.
Our primary interviews span a diverse range of company types essential to this market:
IVD Instrument & Reagent Manufacturers: Companies specializing in bacterial identification and drug sensitivity testing platforms and associated consumables.
Clinical Diagnostic Service Providers: Large reference laboratories, hospital laboratories, and private diagnostic centers offering bacterial ID/DST services.
Pharmaceutical & Biotechnology Companies: Firms involved in anti-infective drug discovery and development, utilizing these testing methods in their R&D.
Veterinary Diagnostics Specialists: Companies and laboratories focused on bacterial identification and drug sensitivity testing for animal health applications.
Contract Research Organizations (CROs): Firms providing specialized microbiology and infectious disease research services to pharma/biotech clients.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of Clinical Microbiology/Laboratory Director
35%
VP/Director of Infectious Disease R&D
25%
Product Manager, Microbiology Diagnostics
25%
Supply Chain/Procurement Manager, Lab Equipment
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
IVD Instrument & Reagent Manufacturers
35%
Clinical Diagnostic Service Providers
30%
Pharmaceutical & Biotechnology Companies
15%
Veterinary Diagnostics Specialists
10%
Contract Research Organizations (CROs)
10%
Secondary Research & Industry Benchmarking
The secondary research phase accounts for the remaining 20-30% of our data collection, complementing primary insights with robust historical and publicly available information. This phase focuses on a thorough review of published data, financial reports, and regulatory documents to establish a comprehensive baseline for market understanding. Our rigorous approach ensures that all secondary data is vetted against primary findings and internal proprietary databases.
Key secondary sources leveraged include:
Financial Databases: Bloomberg, Factiva, Hoovers, PitchBook for company financials, investment trends, and competitive analysis.
Government & Regulatory Publications: Reports and guidelines from health ministries, regulatory bodies, and public health organizations. Examples include: U.S. Food and Drug Administration (FDA.gov), European Medicines Agency (EMA.europa.eu).
Industry Associations & Non-profit Organizations: Publications, reports, and statistics from leading professional bodies. Relevant examples include: Clinical & Laboratory Standards Institute (CLSI.org), American Society for Microbiology (ASM.org), European Society of Clinical Microbiology and Infectious Diseases (ESCMID.org).
Company Filings & Publications: Annual reports, investor presentations, product catalogs, press releases, and corporate websites of key market players.
Scientific & Academic Literature: Peer-reviewed journals, research papers, and patents related to bacterial identification and drug sensitivity testing technologies.
All reports are updated up to the date of purchase, ensuring the most current market intelligence is provided to our clients.
Demand Modeling & Market Estimation
Our market sizing and forecasting employ a sophisticated combination of top-down and bottom-up methodologies, validated through multi-level data triangulation. This approach ensures robust estimation of the current market size and accurate projection of future growth for the forecast period 2026-2034.
Bottom-up Approach: This method involves estimating market size by aggregating granular data points. Key variables and metrics used include:
Number of Bacterial Identification and Drug Sensitivity Tests Performed Annually: Segmented by application (e.g., clinical, veterinary, food safety) and geographic region.
Average Revenue Per Test/Per Patient Sample: Reflecting pricing models for different testing methods (automated vs. manual) and technologies.
Installed Base of Automated Bacterial ID/DST Instruments: Estimating the existing number of systems and their average utilization rates across end-user segments.
Consumables and Reagents Consumption Per Instrument/Per Test: Crucial for calculating the recurring revenue streams associated with various platforms.
Prevalence and Incidence Rates of Key Bacterial Infections: Directly impacting the demand for diagnostic testing.
Top-down Approach: The top-down approach estimates the overall market size from macro-economic indicators and industry revenue figures, which are then disaggregated to specific segments. This involves analyzing total healthcare expenditure, IVD market trends, and infectious disease diagnostics market sizes.
Multi-level Data Triangulation: This process involves cross-referencing data points derived from primary interviews, secondary sources, and our proprietary internal databases. This rigorous validation minimizes discrepancies and enhances the reliability of our market estimations and forecasts. Our forecasting models incorporate analyses of market drivers, restraints, opportunities, and challenges specific to the bacterial identification and drug sensitivity testing market, alongside macroeconomic factors and technological evolution.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90% for our market reports. This high level of precision is achieved through our robust data validation and quality check mechanisms:
Cross-Validation: Data points collected from primary research are meticulously cross-referenced with multiple secondary sources and our internal proprietary models.
Expert Panel Review: Key findings and market estimations are presented to an internal panel of senior analysts and industry experts for critical review and validation.
Quantitative Modeling: Advanced statistical and econometric models are utilized to analyze historical data, identify trends, and project future market behavior, minimizing subjective bias.
Iterative Refinement: Our methodology involves an iterative process of data collection, analysis, and refinement, allowing for continuous improvement in accuracy and insight depth.
Dynamic Updating: As a standard practice, every report is updated up to the date of purchase, reflecting the latest market developments, competitive shifts, and regulatory changes, ensuring our clients receive the most current and relevant market intelligence.
Frequently Asked Questions
1. Which region dominates the Bacterial Identification and Drug Sensitivity Testing market?
North America leads the Bacterial Identification and Drug Sensitivity Testing market, holding an estimated 35% share. This is driven by advanced healthcare infrastructure, high adoption rates of automated testing methods, and significant R&D investments in diagnostic technologies. The presence of major market players also contributes to its leadership.
2. How are purchasing trends evolving in the Bacterial ID & DST market?
End-users, including hospitals and diagnostic laboratories, increasingly prioritize automated testing systems for efficiency and accuracy. There is a growing demand for integrated solutions that combine identification and sensitivity testing, moving away from manual methods to reduce turnaround times and improve patient outcomes. This shift supports the adoption of consumables and reagents for these advanced platforms.
3. What technological innovations are shaping the Bacterial Identification and DST industry?
The market is experiencing rapid innovation driven by technologies such as Mass Spectrometry, Next-Generation Sequencing (NGS), and advanced PCR. These technologies offer faster, more accurate pathogen identification and drug sensitivity profiling, critical for combating antimicrobial resistance. R&D focuses on developing point-of-care diagnostics and multiplex assays.
4. What are the current pricing trends for Bacterial ID & DST products?
Pricing in the Bacterial Identification and Drug Sensitivity Testing market is influenced by technology complexity and automation levels. While high-throughput automated instruments represent a significant initial investment, their operational cost-efficiency and reduced labor requirements can offset this over time. Consumables and reagents maintain a steady revenue stream, often under long-term supply contracts.
5. Are there notable recent developments in the Bacterial Identification market?
While specific recent M&A or product launches are not detailed in the input, the market is characterized by continuous product enhancements and strategic partnerships among key players. Companies like BioMerieux and Thermo Fisher Scientific consistently invest in improving their diagnostic platforms, focusing on speed, accuracy, and ease of use to address clinical demand.
6. Which disruptive technologies could impact Bacterial ID & DST?
Emerging technologies like CRISPR-based diagnostics and advanced microfluidics hold potential for disruptive impact on Bacterial Identification and Drug Sensitivity Testing. These aim to provide ultra-rapid, highly portable, and cost-effective solutions for pathogen detection and resistance profiling, potentially challenging established lab-based methodologies in the future.