Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Bio-Based UV-Curable Resin by Resin Type (Bio-Based Epoxy Acrylates, Bio-Based Polyester Acrylates, Bio-Based Polyurethane Acrylates, Others), by Feedstock Source (Vegetable Oils, Lignin-Based Derivatives, Protein-Based Sources, Others), by Formulation (Solvent-Free, Waterborne UV Resins, Solvent-Based UV Resins), by Application (Coatings, Inks, Adhesives & Sealants, 3D Printing, Others), by End-Use Industry (Packaging, Automotive & Transportation, Electronics & Electrical, Building & Construction, Furniture & Woodworking, Healthcare & Medical, Textile Industry, Industrial Manufacturing, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 3, 2026|Base Year : 2025|Pages : 112
Key Insights into Bio-Based UV-Curable Resin Market
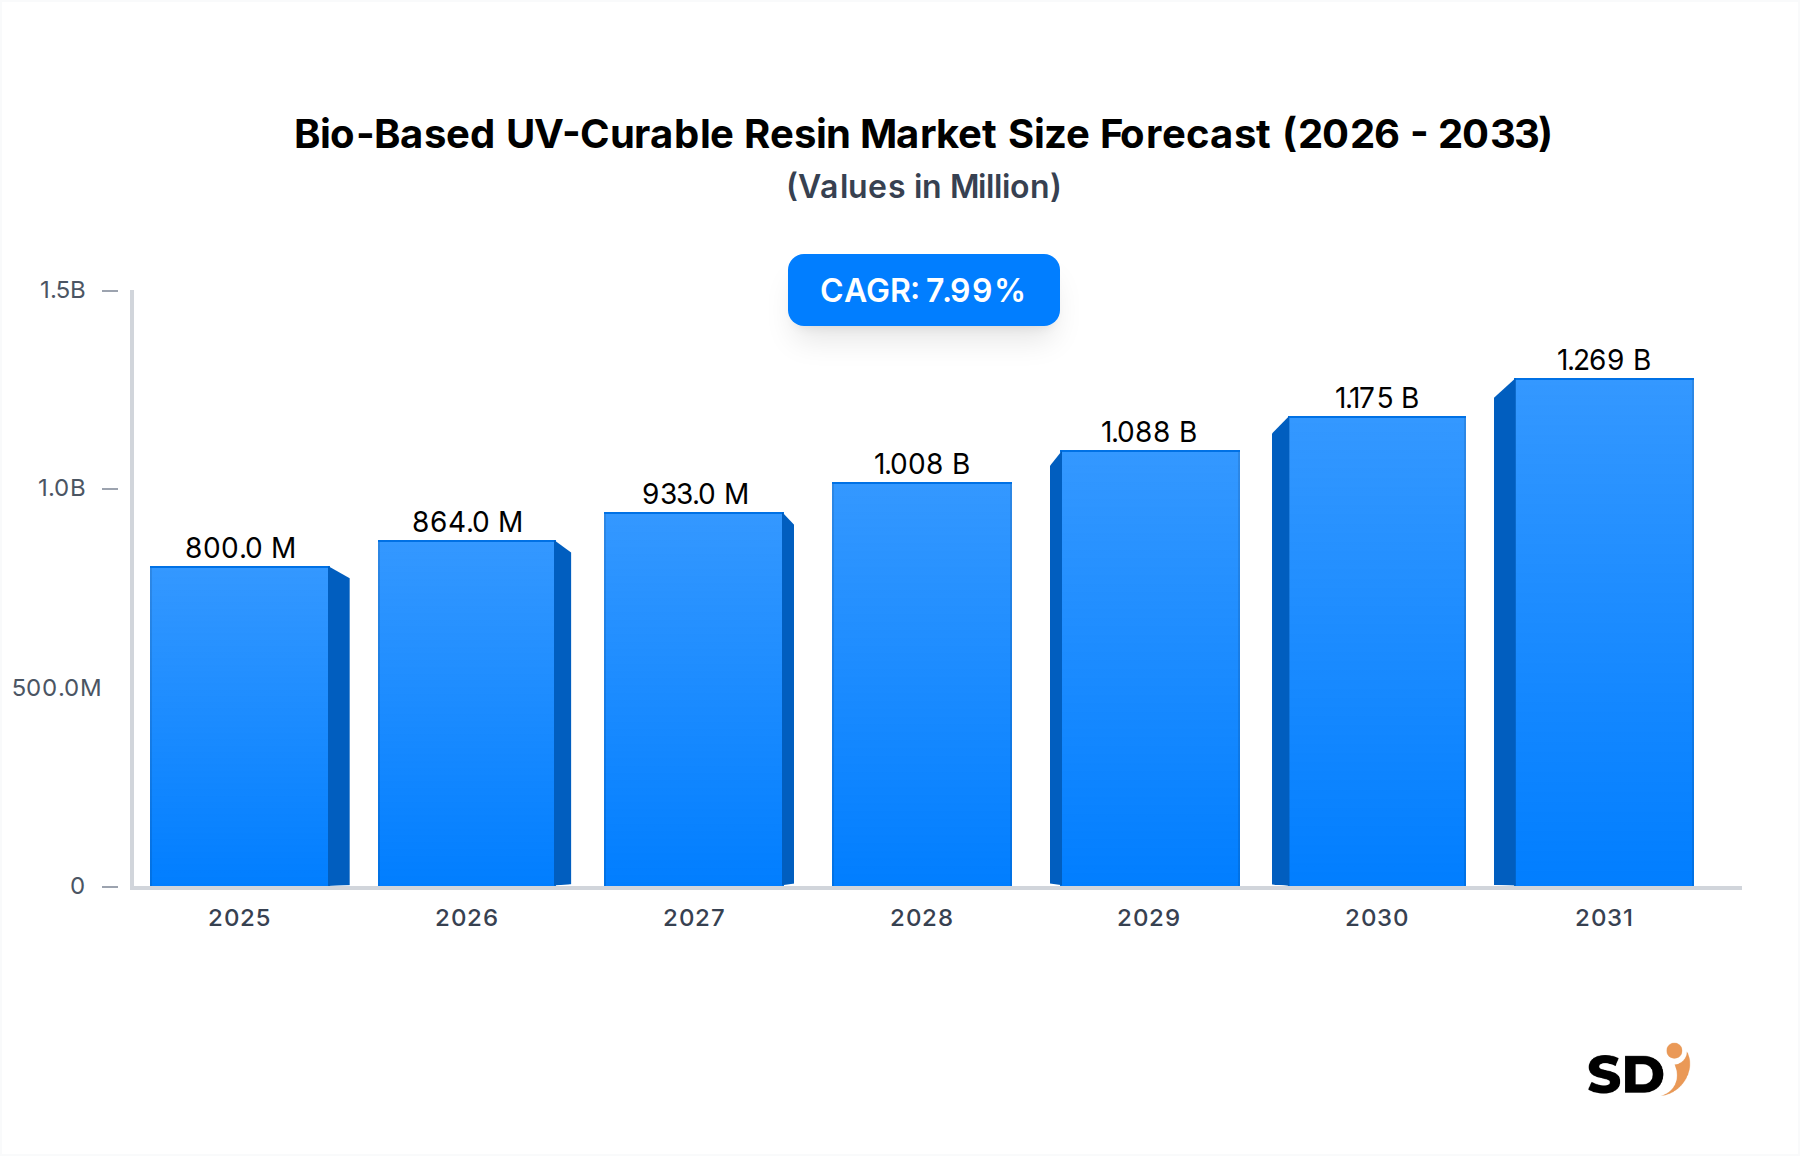
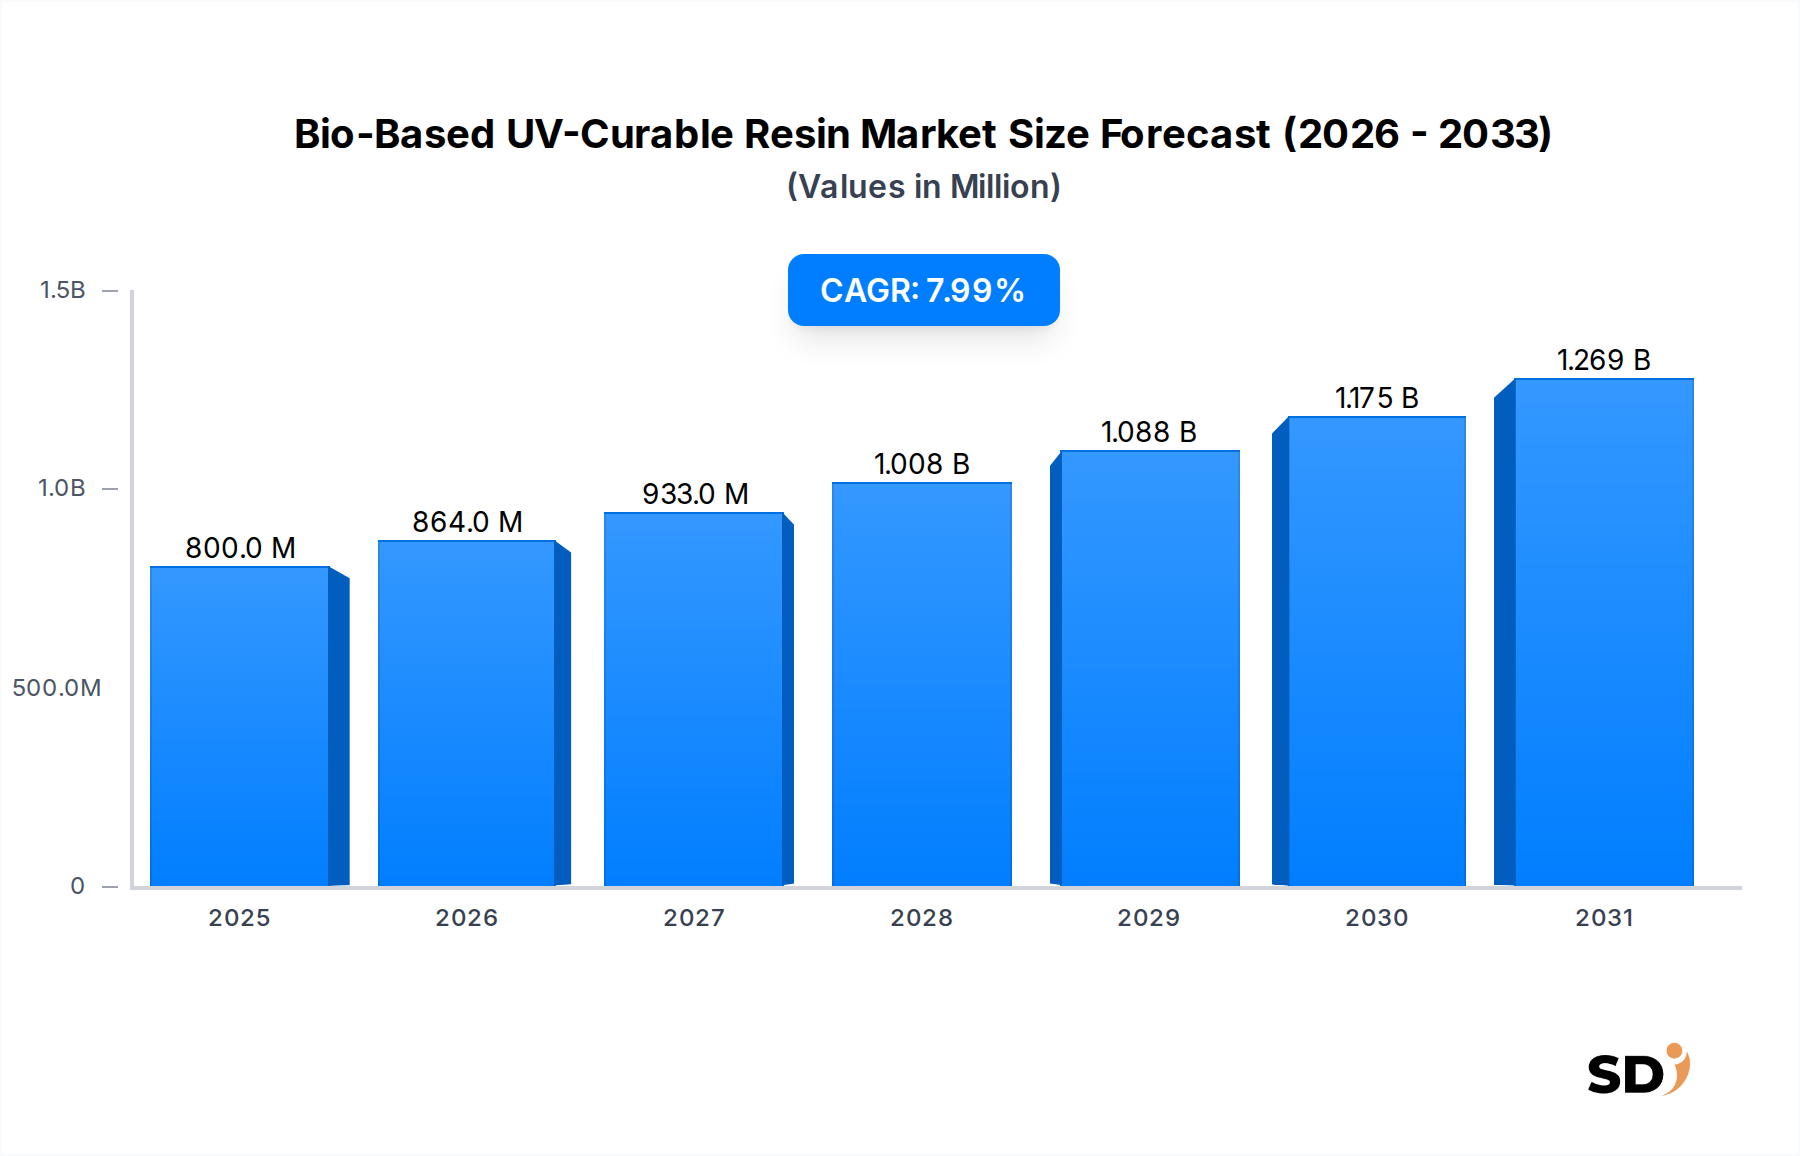
The Bio-Based UV-Curable Resin Market is experiencing robust expansion, driven by an escalating demand for sustainable and environmentally benign material solutions across diverse end-use industries. As per our comprehensive analysis, the market is poised to demonstrate a compound annual growth rate (CAGR) of 8% over the forecast period. The estimated current valuation of the Bio-Based UV-Curable Resin Market stands at approximately $370.55 million in 2023, projected to reach a significant $800 million by 2033. This substantial growth trajectory is underpinned by several critical demand drivers and macro tailwinds.
Bio-Based UV-Curable Resin Market Size (In Million)
1.5B
1.0B
500.0M
0
800.0 M
2025
864.0 M
2026
933.0 M
2027
1.008 B
2028
1.088 B
2029
1.175 B
2030
1.269 B
2031
Key drivers include the global imperative for reducing volatile organic compound (VOC) emissions, stringent environmental regulations pushing industries towards greener alternatives, and a heightened corporate focus on Environmental, Social, and Governance (ESG) initiatives. Bio-based UV-curable resins offer a compelling solution, marrying rapid curing capabilities and high performance with reduced petrochemical reliance and lower carbon footprints. The expanding application scope, particularly in advanced coatings, inks, adhesives, and notably the rapidly evolving 3D printing sector, further fuels market momentum. Innovations in feedstock sourcing, utilizing renewable resources like vegetable oils and agricultural byproducts, are enhancing the cost-effectiveness and performance profiles of these resins, challenging the dominance of conventional petroleum-based alternatives. Moreover, continuous research and development efforts are addressing performance gaps, particularly in terms of durability and chemical resistance for highly demanding applications, thus broadening their adoption across sectors such as automotive, electronics, and construction. The strategic shift towards a circular economy model by major industrial players is creating a sustained demand for bio-based solutions, positioning the Bio-Based UV-Curable Resin Market for sustained and significant growth in the coming decade.
Dominant Application Segment: Coatings in Bio-Based UV-Curable Resin Market
The coatings application segment currently holds the largest revenue share within the Bio-Based UV-Curable Resin Market, demonstrating a pervasive influence across numerous end-use industries. This dominance is primarily attributable to the superior performance characteristics of UV-curable resins, such as rapid curing times, excellent scratch and chemical resistance, and the ability to achieve high-gloss finishes with minimal VOC emissions. When these attributes are combined with bio-based feedstocks, the resulting resins present an environmentally responsible alternative to traditional coating systems. The widespread adoption of these coatings spans across sectors like furniture and woodworking, automotive, packaging, and industrial manufacturing, where high-performance and quick turnaround times are paramount.
Within the coatings sector, key players such as Allnex, Sartomer (part of Arkema S.A.), and IGM Resins have been instrumental in driving innovation and market penetration. These companies continually invest in R&D to enhance the bio-content and performance of their resin formulations, ensuring parity, and in some cases, superiority, over their petrochemical counterparts. The demand for sustainable Packaging Coatings Market solutions, in particular, is a significant growth engine for bio-based UV-curable resins, as brand owners seek to improve the ecological footprint of their products. Similarly, the automotive industry's push for lightweighting and durable yet sustainable finishes is contributing to the segment's expansion. The coatings segment is not only dominating in terms of current revenue but is also anticipated to maintain its leading position and grow significantly, spurred by ongoing advancements in Bio-Based Epoxy Acrylates Market and Waterborne UV Resins Market formulations. The market share of bio-based UV-curable coatings is consistently expanding as industries transition away from traditional UV Curable Resins Market derived solely from fossil fuels, striving for better environmental compliance and consumer acceptance. This segment's growth reflects a broader industry trend towards a Sustainable Coatings Market landscape, where performance and ecological responsibility are no longer mutually exclusive.
Key Market Drivers & Constraints in Bio-Based UV-Curable Resin Market
Several potent market drivers are propelling the expansion of the Bio-Based UV-Curable Resin Market, alongside specific constraints that temper its growth. A primary driver is the global regulatory push for reduced environmental impact. Directives such as the European Union's REACH regulations and various EPA standards in North America impose stringent limits on VOC emissions, forcing industries to seek low-VOC or VOC-free solutions. Bio-based UV-curable resins, often formulated as solvent-free or waterborne, align perfectly with these regulatory frameworks, promoting their adoption. Furthermore, increasing consumer awareness and corporate sustainability agendas (ESG mandates) drive demand for products with a lower carbon footprint and reduced reliance on fossil resources. This societal shift is quantifiable through the rising investment in green technologies and certified sustainable materials across numerous industries. Advancements in biotechnology and chemical synthesis are also making bio-based feedstocks more accessible and cost-effective. For instance, the growing availability and improved processing of raw materials from the Vegetable Oils Market, such as soybean oil and castor oil, alongside innovations in leveraging the Lignin Derivatives Market, are significantly enhancing the viability and scalability of bio-based resin production.
However, the market faces notable constraints. The initial cost of bio-based UV-curable resins can be significantly higher compared to conventional petrochemical-based UV resins, primarily due to the complexities of raw material processing and smaller production scales. This cost differential can deter adoption, especially in price-sensitive applications. Another constraint pertains to the perceived or actual performance gaps in highly specialized or demanding applications where traditional resins have established benchmarks for durability, chemical resistance, and adhesion. While rapid advancements are bridging these gaps, overcoming historical perceptions requires extensive validation and market education. Lastly, the scalability and consistent supply chain for certain bio-based raw materials, particularly those reliant on agricultural cycles or nascent biotechnological processes, can present challenges, leading to price volatility and potential supply disruptions for manufacturers in the Specialty Chemicals Market.
Competitive Ecosystem of Bio-Based UV-Curable Resin Market
The competitive landscape of the Bio-Based UV-Curable Resin Market is characterized by a mix of established chemical giants and specialized innovators, all vying for market share through product differentiation and strategic partnerships. Companies are focusing on expanding their bio-based product portfolios and improving performance to match or exceed traditional resins.
Covestro: A leading polymer company, Covestro AG is a significant player with a focus on sustainable solutions, offering a range of bio-based polyurethane and other acrylic resins for coatings, adhesives, and 3D printing applications, leveraging its extensive R&D capabilities.
Allnex: A global leader in industrial coating resins, Allnex GmbH provides a broad portfolio of conventional and bio-based UV-curable resins, emphasizing high-performance and environmental sustainability for diverse applications like wood, plastic, and metal coatings.
Creality: While primarily known for 3D printers, Creality’s presence in this market is through its development of bio-based UV-curable photopolymer resins tailored for additive manufacturing, supporting the growth of sustainable 3D printing solutions.
Uniformation: This company contributes to the market through its expertise in developing and manufacturing advanced materials, including specific bio-based resin formulations for niche industrial applications, often focused on specialized performance attributes.
Changxing Materials: A key player in the Asia Pacific region, Changxing Materials develops and supplies various coating resins, including a growing range of bio-based UV-curable options, catering to industries such as electronics and packaging.
Sartomer: A business line of Arkema S.A., Sartomer is a global leader in specialty acrylate and methacrylate monomers and oligomers, with an increasing focus on developing and commercializing high-performance bio-based UV-curable resins for coatings, inks, and adhesives.
IGM Resins: Specializing in energy curing solutions, IGM Resins offers a comprehensive portfolio of UV-curable materials, actively expanding its bio-based offerings to meet the rising demand for sustainable and efficient curing technologies across various industries.
BASF SE: As one of the world's largest chemical producers, BASF SE actively participates in the development and supply of bio-based chemical intermediates and resins, including components for UV-curable systems, aligning with its broader sustainability goals.
Arkema S.A.: A global specialty chemicals and advanced materials company, Arkema S.A., through its Sartomer brand, is a crucial innovator in bio-based UV-curable resins, focusing on performance polymers derived from renewable resources.
DSM-Firmenich: Following their merger, DSM-Firmenich combines expertise in health, nutrition, and bioscience, with their materials science division likely contributing to the development of novel bio-based components for advanced resin systems.
Evonik Industries AG: This specialty chemicals company is involved in numerous bio-based initiatives, offering raw materials and system components that contribute to the formulation of sustainable UV-curable resins for various high-performance applications.
Recent Developments & Milestones in Bio-Based UV-Curable Resin Market
October 2024: Allnex introduced a new series of bio-based UV-curable oligomers derived from sustainable vegetable oils, specifically engineered for high-performance wood coatings, offering enhanced hardness and chemical resistance with up to 70% bio-content.
August 2024: Sartomer announced a strategic partnership with a leading agricultural biotechnology firm to secure a stable and scalable supply of novel bio-derived intermediates, aiming to accelerate the development of next-generation Bio-Based Epoxy Acrylates Market solutions.
June 2024: Covestro launched a new line of partially bio-based UV-curable polyurethane dispersions (PUDs) designed for flexible packaging and textile applications, providing excellent adhesion and elongation properties while reducing reliance on fossil resources.
April 2024: IGM Resins expanded its technical service center in Asia Pacific to focus on accelerating the development and formulation support for bio-based UV-curable inks and coatings, catering to the region's rapidly growing industrial sector.
January 2024: A consortium of academic institutions and industry players, including BASF SE and Evonik Industries AG, received substantial EU funding for a collaborative project aimed at optimizing enzymatic processes for producing bio-based monomers for UV-curable resins, targeting industrial scale-up.
November 2023: Creality unveiled a new range of bio-based photopolymer resins specifically for desktop 3D printing applications, offering improved biodegradability and lower odor profiles, addressing environmental concerns in the consumer 3D Printing Materials Market.
September 2023: Changxing Materials reported a significant increase in its production capacity for waterborne bio-based UV resins, responding to surging demand from the Chinese electronics and automotive interior coatings markets.
Regional Market Breakdown for Bio-Based UV-Curable Resin Market
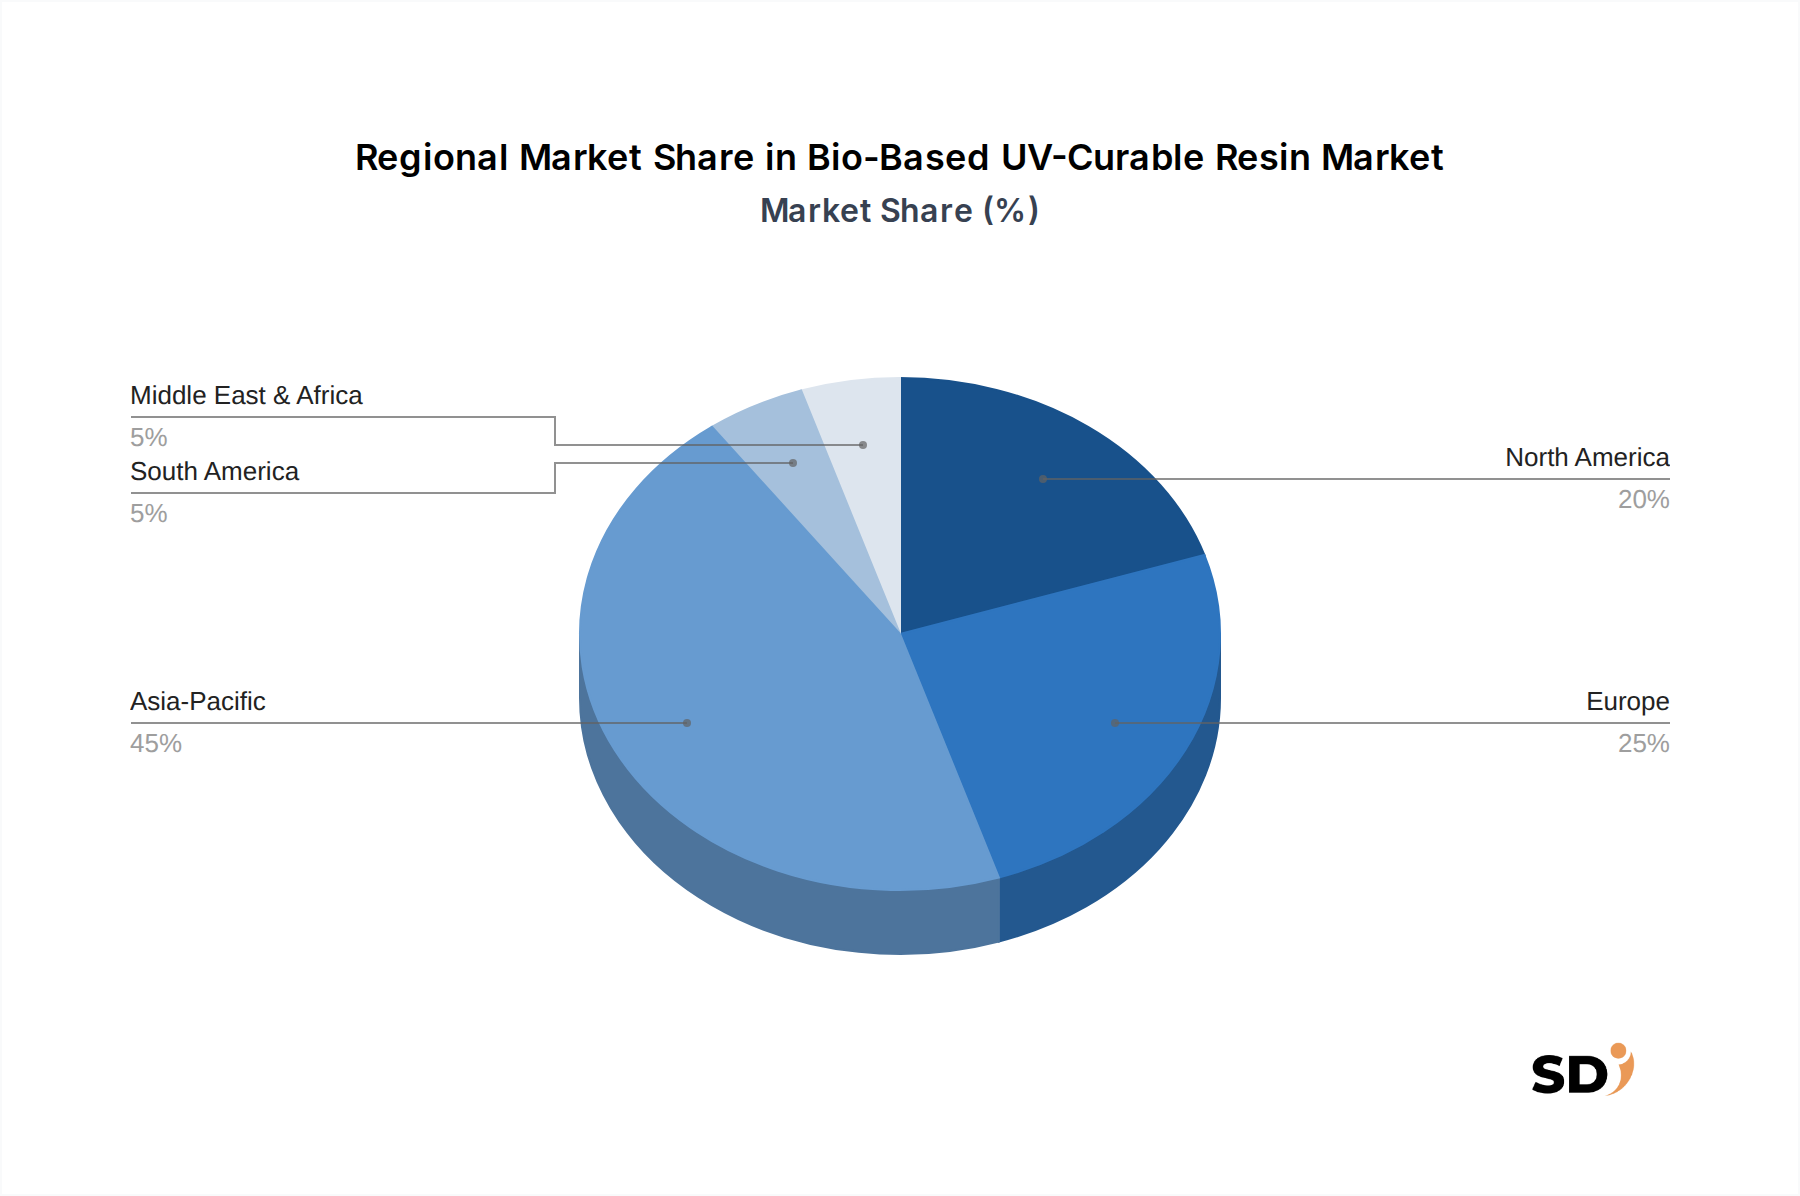
The Bio-Based UV-Curable Resin Market exhibits distinct regional dynamics, influenced by varying regulatory landscapes, industrial development, and sustainability commitments. Asia Pacific emerges as the largest and fastest-growing region in the Bio-Based UV-Curable Resin Market, driven by its extensive manufacturing base, rapid industrialization, and a growing emphasis on sustainable practices across sectors like packaging, automotive, and electronics. Countries like China, India, and Japan are investing heavily in green chemical production and adopting bio-based solutions to mitigate environmental pollution. This region is projected to command over 40% of the global market share by 2033, with a regional CAGR estimated above 9%, fueled by expanding consumer electronics and the burgeoning Packaging Coatings Market.
Europe holds a substantial market share, second only to Asia Pacific, characterized by stringent environmental regulations (e.g., EU Green Deal, REACH) and a strong public and corporate commitment to sustainability. The region is a hub for innovation in green chemistry and advanced materials, with robust demand from the furniture, automotive, and industrial coatings industries. The European market is expected to grow at a CAGR of approximately 7.5%, driven by the transition towards a circular economy and the high uptake of Sustainable Coatings Market solutions. North America also represents a significant market, influenced by progressive environmental policies, particularly in states like California, and a strong push towards sustainable manufacturing across diverse industries. The region sees considerable adoption in 3D Printing Materials Market and high-performance coatings, with an anticipated CAGR around 7%.
The Middle East & Africa and South America regions currently account for smaller shares but are expected to demonstrate promising growth rates. South America, particularly Brazil, with its abundant bio-resources, is poised for growth as local industries seek cost-effective and sustainable material solutions. The Middle East & Africa region's growth is largely driven by diversification efforts away from fossil fuels and increasing infrastructure development projects prioritizing green building materials and coatings. The collective CAGR for these emerging regions is projected to exceed 6.5%.
Supply Chain & Raw Material Dynamics for Bio-Based UV-Curable Resin Market
The supply chain for the Bio-Based UV-Curable Resin Market is intricately linked to the availability and price volatility of its upstream raw materials, which are primarily derived from renewable sources. Key feedstocks include various components from the Vegetable Oils Market, such as soybean oil, castor oil, and sunflower oil, which are processed into bio-polyols, bio-epoxies, and other intermediates. Lignin-based derivatives, sourced from biomass, also play a crucial role, particularly in developing aromatic structures for enhanced resin performance. Additionally, carbohydrate-based feedstocks and protein-based sources are gaining traction for niche applications.
The primary sourcing risks stem from the inherent volatility of agricultural commodity markets. Factors such as weather patterns, geopolitical events affecting trade routes, and fluctuating demand for food-grade oils can significantly impact the price and availability of vegetable oil-based feedstocks. This can lead to price instability for manufacturers, potentially increasing the final cost of bio-based resins compared to petrochemical alternatives. Historically, disruptions in agricultural supply chains or sudden shifts in commodity prices have led to procurement challenges for resin producers, forcing them to diversify their raw material sources or absorb higher costs. The nascent stage of large-scale commercialization for some advanced bio-based intermediates, such as specific Lignin Derivatives Market components, also poses supply consistency risks. These dynamics necessitate robust supply chain management, including long-term contracts with suppliers, investment in regional sourcing, and continuous research into alternative bio-based feedstocks to mitigate potential disruptions and stabilize costs within the broader Specialty Chemicals Market.
Investment & Funding Activity in Bio-Based UV-Curable Resin Market
Investment and funding activity in the Bio-Based UV-Curable Resin Market have seen a notable uptick over the past 2-3 years, reflecting growing confidence in sustainable chemical technologies. Venture capital firms and corporate strategic investors are increasingly allocating capital towards startups and innovative projects focused on novel bio-based feedstocks and advanced resin formulations. For instance, several biotech companies developing enzymatic processes for creating bio-monomers from agricultural waste have secured significant Series A and B funding rounds, aiming to reduce production costs and enhance scalability. M&A activity has also been observed, primarily driven by large chemical conglomerates seeking to expand their green portfolio and acquire specialized expertise. Major players are strategically acquiring smaller, innovative firms with patented bio-based technologies or unique production capabilities to gain a competitive edge in the Sustainable Coatings Market and related applications.
Strategic partnerships between raw material suppliers, resin manufacturers, and end-use industry leaders are another prominent trend. These collaborations often involve joint development agreements (JDAs) to tailor bio-based UV-curable resins for specific high-growth applications like automotive interior coatings or high-performance 3D Printing Materials Market. For example, a partnership between a leading automotive OEM and a bio-resin producer to develop durable, bio-based UV-curable clear coats signals a strong commitment to integrating these materials into mainstream products. The sub-segments attracting the most capital are those offering clear performance advantages, significant sustainability impacts, or potential for cost reduction through process innovation. This includes investments in lignin valorization technologies, advanced bio-polyol synthesis, and novel Waterborne UV Resins Market formulations, all aligning with the broader Green Chemistry Market trend towards eco-efficient and resource-saving solutions.
Bio-Based UV-Curable Resin Segmentation
1. Resin Type
1.1. Bio-Based Epoxy Acrylates
1.2. Bio-Based Polyester Acrylates
1.3. Bio-Based Polyurethane Acrylates
1.4. Others
2. Feedstock Source
2.1. Vegetable Oils
2.2. Lignin-Based Derivatives
2.3. Protein-Based Sources
2.4. Others
3. Formulation
3.1. Solvent-Free
3.2. Waterborne UV Resins
3.3. Solvent-Based UV Resins
4. Application
4.1. Coatings
4.2. Inks
4.3. Adhesives & Sealants
4.4. 3D Printing
4.5. Others
5. End-Use Industry
5.1. Packaging
5.2. Automotive & Transportation
5.3. Electronics & Electrical
5.4. Building & Construction
5.5. Furniture & Woodworking
5.6. Healthcare & Medical
5.7. Textile Industry
5.8. Industrial Manufacturing
5.9. Others
Bio-Based UV-Curable Resin Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Bio-Based UV-Curable Resin REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8% from 2020-2034
Segmentation
By Resin Type
Bio-Based Epoxy Acrylates
Bio-Based Polyester Acrylates
Bio-Based Polyurethane Acrylates
Others
By Feedstock Source
Vegetable Oils
Lignin-Based Derivatives
Protein-Based Sources
Others
By Formulation
Solvent-Free
Waterborne UV Resins
Solvent-Based UV Resins
By Application
Coatings
Inks
Adhesives & Sealants
3D Printing
Others
By End-Use Industry
Packaging
Automotive & Transportation
Electronics & Electrical
Building & Construction
Furniture & Woodworking
Healthcare & Medical
Textile Industry
Industrial Manufacturing
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Resin Type
5.1.1. Bio-Based Epoxy Acrylates
5.1.2. Bio-Based Polyester Acrylates
5.1.3. Bio-Based Polyurethane Acrylates
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Feedstock Source
5.2.1. Vegetable Oils
5.2.2. Lignin-Based Derivatives
5.2.3. Protein-Based Sources
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Formulation
5.3.1. Solvent-Free
5.3.2. Waterborne UV Resins
5.3.3. Solvent-Based UV Resins
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Coatings
5.4.2. Inks
5.4.3. Adhesives & Sealants
5.4.4. 3D Printing
5.4.5. Others
5.5. Market Analysis, Insights and Forecast - by End-Use Industry
5.5.1. Packaging
5.5.2. Automotive & Transportation
5.5.3. Electronics & Electrical
5.5.4. Building & Construction
5.5.5. Furniture & Woodworking
5.5.6. Healthcare & Medical
5.5.7. Textile Industry
5.5.8. Industrial Manufacturing
5.5.9. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. South America
5.6.3. Europe
5.6.4. Middle East & Africa
5.6.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Resin Type
6.1.1. Bio-Based Epoxy Acrylates
6.1.2. Bio-Based Polyester Acrylates
6.1.3. Bio-Based Polyurethane Acrylates
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Feedstock Source
6.2.1. Vegetable Oils
6.2.2. Lignin-Based Derivatives
6.2.3. Protein-Based Sources
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by Formulation
6.3.1. Solvent-Free
6.3.2. Waterborne UV Resins
6.3.3. Solvent-Based UV Resins
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Coatings
6.4.2. Inks
6.4.3. Adhesives & Sealants
6.4.4. 3D Printing
6.4.5. Others
6.5. Market Analysis, Insights and Forecast - by End-Use Industry
6.5.1. Packaging
6.5.2. Automotive & Transportation
6.5.3. Electronics & Electrical
6.5.4. Building & Construction
6.5.5. Furniture & Woodworking
6.5.6. Healthcare & Medical
6.5.7. Textile Industry
6.5.8. Industrial Manufacturing
6.5.9. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Resin Type
7.1.1. Bio-Based Epoxy Acrylates
7.1.2. Bio-Based Polyester Acrylates
7.1.3. Bio-Based Polyurethane Acrylates
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Feedstock Source
7.2.1. Vegetable Oils
7.2.2. Lignin-Based Derivatives
7.2.3. Protein-Based Sources
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by Formulation
7.3.1. Solvent-Free
7.3.2. Waterborne UV Resins
7.3.3. Solvent-Based UV Resins
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Coatings
7.4.2. Inks
7.4.3. Adhesives & Sealants
7.4.4. 3D Printing
7.4.5. Others
7.5. Market Analysis, Insights and Forecast - by End-Use Industry
7.5.1. Packaging
7.5.2. Automotive & Transportation
7.5.3. Electronics & Electrical
7.5.4. Building & Construction
7.5.5. Furniture & Woodworking
7.5.6. Healthcare & Medical
7.5.7. Textile Industry
7.5.8. Industrial Manufacturing
7.5.9. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Resin Type
8.1.1. Bio-Based Epoxy Acrylates
8.1.2. Bio-Based Polyester Acrylates
8.1.3. Bio-Based Polyurethane Acrylates
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Feedstock Source
8.2.1. Vegetable Oils
8.2.2. Lignin-Based Derivatives
8.2.3. Protein-Based Sources
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by Formulation
8.3.1. Solvent-Free
8.3.2. Waterborne UV Resins
8.3.3. Solvent-Based UV Resins
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Coatings
8.4.2. Inks
8.4.3. Adhesives & Sealants
8.4.4. 3D Printing
8.4.5. Others
8.5. Market Analysis, Insights and Forecast - by End-Use Industry
8.5.1. Packaging
8.5.2. Automotive & Transportation
8.5.3. Electronics & Electrical
8.5.4. Building & Construction
8.5.5. Furniture & Woodworking
8.5.6. Healthcare & Medical
8.5.7. Textile Industry
8.5.8. Industrial Manufacturing
8.5.9. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Resin Type
9.1.1. Bio-Based Epoxy Acrylates
9.1.2. Bio-Based Polyester Acrylates
9.1.3. Bio-Based Polyurethane Acrylates
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Feedstock Source
9.2.1. Vegetable Oils
9.2.2. Lignin-Based Derivatives
9.2.3. Protein-Based Sources
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by Formulation
9.3.1. Solvent-Free
9.3.2. Waterborne UV Resins
9.3.3. Solvent-Based UV Resins
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Coatings
9.4.2. Inks
9.4.3. Adhesives & Sealants
9.4.4. 3D Printing
9.4.5. Others
9.5. Market Analysis, Insights and Forecast - by End-Use Industry
9.5.1. Packaging
9.5.2. Automotive & Transportation
9.5.3. Electronics & Electrical
9.5.4. Building & Construction
9.5.5. Furniture & Woodworking
9.5.6. Healthcare & Medical
9.5.7. Textile Industry
9.5.8. Industrial Manufacturing
9.5.9. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Resin Type
10.1.1. Bio-Based Epoxy Acrylates
10.1.2. Bio-Based Polyester Acrylates
10.1.3. Bio-Based Polyurethane Acrylates
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Feedstock Source
10.2.1. Vegetable Oils
10.2.2. Lignin-Based Derivatives
10.2.3. Protein-Based Sources
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by Formulation
10.3.1. Solvent-Free
10.3.2. Waterborne UV Resins
10.3.3. Solvent-Based UV Resins
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Coatings
10.4.2. Inks
10.4.3. Adhesives & Sealants
10.4.4. 3D Printing
10.4.5. Others
10.5. Market Analysis, Insights and Forecast - by End-Use Industry
10.5.1. Packaging
10.5.2. Automotive & Transportation
10.5.3. Electronics & Electrical
10.5.4. Building & Construction
10.5.5. Furniture & Woodworking
10.5.6. Healthcare & Medical
10.5.7. Textile Industry
10.5.8. Industrial Manufacturing
10.5.9. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Covestro
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Allnex
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Creality
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Uniformation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Changxing Materials
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Sartomer
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. IGM Resins
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. BASF SE
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Covestro AG
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Arkema S.A.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Allnex GmbH
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. DSM-Firmenich
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Evonik Industries AG
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. IGM Resins
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Bio-Based UV-Curable Resin Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Bio-Based UV-Curable Resin Revenue (million), by Resin Type 2026 & 2034
Figure 3: North America Bio-Based UV-Curable Resin Revenue Share (%), by Resin Type 2026 & 2034
Figure 4: North America Bio-Based UV-Curable Resin Revenue (million), by Feedstock Source 2026 & 2034
Figure 5: North America Bio-Based UV-Curable Resin Revenue Share (%), by Feedstock Source 2026 & 2034
Figure 6: North America Bio-Based UV-Curable Resin Revenue (million), by Formulation 2026 & 2034
Figure 7: North America Bio-Based UV-Curable Resin Revenue Share (%), by Formulation 2026 & 2034
Figure 8: North America Bio-Based UV-Curable Resin Revenue (million), by Application 2026 & 2034
Figure 9: North America Bio-Based UV-Curable Resin Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Bio-Based UV-Curable Resin Revenue (million), by End-Use Industry 2026 & 2034
Figure 11: North America Bio-Based UV-Curable Resin Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 12: North America Bio-Based UV-Curable Resin Revenue (million), by Country 2026 & 2034
Figure 13: North America Bio-Based UV-Curable Resin Revenue Share (%), by Country 2026 & 2034
Figure 14: South America Bio-Based UV-Curable Resin Revenue (million), by Resin Type 2026 & 2034
Figure 15: South America Bio-Based UV-Curable Resin Revenue Share (%), by Resin Type 2026 & 2034
Figure 16: South America Bio-Based UV-Curable Resin Revenue (million), by Feedstock Source 2026 & 2034
Figure 17: South America Bio-Based UV-Curable Resin Revenue Share (%), by Feedstock Source 2026 & 2034
Figure 18: South America Bio-Based UV-Curable Resin Revenue (million), by Formulation 2026 & 2034
Figure 19: South America Bio-Based UV-Curable Resin Revenue Share (%), by Formulation 2026 & 2034
Figure 20: South America Bio-Based UV-Curable Resin Revenue (million), by Application 2026 & 2034
Figure 21: South America Bio-Based UV-Curable Resin Revenue Share (%), by Application 2026 & 2034
Figure 22: South America Bio-Based UV-Curable Resin Revenue (million), by End-Use Industry 2026 & 2034
Figure 23: South America Bio-Based UV-Curable Resin Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 24: South America Bio-Based UV-Curable Resin Revenue (million), by Country 2026 & 2034
Figure 25: South America Bio-Based UV-Curable Resin Revenue Share (%), by Country 2026 & 2034
Figure 26: Europe Bio-Based UV-Curable Resin Revenue (million), by Resin Type 2026 & 2034
Figure 27: Europe Bio-Based UV-Curable Resin Revenue Share (%), by Resin Type 2026 & 2034
Figure 28: Europe Bio-Based UV-Curable Resin Revenue (million), by Feedstock Source 2026 & 2034
Figure 29: Europe Bio-Based UV-Curable Resin Revenue Share (%), by Feedstock Source 2026 & 2034
Figure 30: Europe Bio-Based UV-Curable Resin Revenue (million), by Formulation 2026 & 2034
Figure 31: Europe Bio-Based UV-Curable Resin Revenue Share (%), by Formulation 2026 & 2034
Figure 32: Europe Bio-Based UV-Curable Resin Revenue (million), by Application 2026 & 2034
Figure 33: Europe Bio-Based UV-Curable Resin Revenue Share (%), by Application 2026 & 2034
Figure 34: Europe Bio-Based UV-Curable Resin Revenue (million), by End-Use Industry 2026 & 2034
Figure 35: Europe Bio-Based UV-Curable Resin Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 36: Europe Bio-Based UV-Curable Resin Revenue (million), by Country 2026 & 2034
Figure 37: Europe Bio-Based UV-Curable Resin Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Bio-Based UV-Curable Resin Revenue (million), by Resin Type 2026 & 2034
Figure 39: Middle East & Africa Bio-Based UV-Curable Resin Revenue Share (%), by Resin Type 2026 & 2034
Figure 40: Middle East & Africa Bio-Based UV-Curable Resin Revenue (million), by Feedstock Source 2026 & 2034
Figure 41: Middle East & Africa Bio-Based UV-Curable Resin Revenue Share (%), by Feedstock Source 2026 & 2034
Figure 42: Middle East & Africa Bio-Based UV-Curable Resin Revenue (million), by Formulation 2026 & 2034
Figure 43: Middle East & Africa Bio-Based UV-Curable Resin Revenue Share (%), by Formulation 2026 & 2034
Figure 44: Middle East & Africa Bio-Based UV-Curable Resin Revenue (million), by Application 2026 & 2034
Figure 45: Middle East & Africa Bio-Based UV-Curable Resin Revenue Share (%), by Application 2026 & 2034
Figure 46: Middle East & Africa Bio-Based UV-Curable Resin Revenue (million), by End-Use Industry 2026 & 2034
Figure 47: Middle East & Africa Bio-Based UV-Curable Resin Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 48: Middle East & Africa Bio-Based UV-Curable Resin Revenue (million), by Country 2026 & 2034
Figure 49: Middle East & Africa Bio-Based UV-Curable Resin Revenue Share (%), by Country 2026 & 2034
Figure 50: Asia Pacific Bio-Based UV-Curable Resin Revenue (million), by Resin Type 2026 & 2034
Figure 51: Asia Pacific Bio-Based UV-Curable Resin Revenue Share (%), by Resin Type 2026 & 2034
Figure 52: Asia Pacific Bio-Based UV-Curable Resin Revenue (million), by Feedstock Source 2026 & 2034
Figure 53: Asia Pacific Bio-Based UV-Curable Resin Revenue Share (%), by Feedstock Source 2026 & 2034
Figure 54: Asia Pacific Bio-Based UV-Curable Resin Revenue (million), by Formulation 2026 & 2034
Figure 55: Asia Pacific Bio-Based UV-Curable Resin Revenue Share (%), by Formulation 2026 & 2034
Figure 56: Asia Pacific Bio-Based UV-Curable Resin Revenue (million), by Application 2026 & 2034
Figure 57: Asia Pacific Bio-Based UV-Curable Resin Revenue Share (%), by Application 2026 & 2034
Figure 58: Asia Pacific Bio-Based UV-Curable Resin Revenue (million), by End-Use Industry 2026 & 2034
Figure 59: Asia Pacific Bio-Based UV-Curable Resin Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 60: Asia Pacific Bio-Based UV-Curable Resin Revenue (million), by Country 2026 & 2034
Figure 61: Asia Pacific Bio-Based UV-Curable Resin Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Bio-Based UV-Curable Resin Revenue million Forecast, by Resin Type 2020 & 2034
Table 2: Bio-Based UV-Curable Resin Revenue million Forecast, by Feedstock Source 2020 & 2034
Table 3: Bio-Based UV-Curable Resin Revenue million Forecast, by Formulation 2020 & 2034
Table 4: Bio-Based UV-Curable Resin Revenue million Forecast, by Application 2020 & 2034
Table 5: Bio-Based UV-Curable Resin Revenue million Forecast, by End-Use Industry 2020 & 2034
Table 6: Bio-Based UV-Curable Resin Revenue million Forecast, by Region 2020 & 2034
Table 7: North America Bio-Based UV-Curable Resin Revenue million Forecast, by Resin Type 2020 & 2034
Table 8: North America Bio-Based UV-Curable Resin Revenue million Forecast, by Feedstock Source 2020 & 2034
Table 9: North America Bio-Based UV-Curable Resin Revenue million Forecast, by Formulation 2020 & 2034
Table 10: North America Bio-Based UV-Curable Resin Revenue million Forecast, by Application 2020 & 2034
Table 11: North America Bio-Based UV-Curable Resin Revenue million Forecast, by End-Use Industry 2020 & 2034
Table 12: North America Bio-Based UV-Curable Resin Revenue million Forecast, by Country 2020 & 2034
Table 13: United States Bio-Based UV-Curable Resin Revenue (million) Forecast, by Application 2020 & 2034
Table 64: Rest of Asia Pacific Bio-Based UV-Curable Resin Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
This report heavily emphasizes primary research, constituting approximately 75% of the total research effort. Our approach involves extensive engagement with key industry participants across the value chain to gather first-hand market intelligence, validate secondary findings, and derive nuanced insights directly from experts. This ensures our data reflects the most current market conditions and sentiment.
Targeted Interviewees & Stakeholders: We conducted in-depth, semi-structured interviews with a diverse group of stakeholders, carefully selected based on their profound knowledge and strategic positions within the bio-based UV-curable resin ecosystem. Key roles interviewed included:
Company Types Engaged: Primary interviews spanned a comprehensive range of companies crucial to the bio-based UV-curable resin value chain, ensuring a holistic understanding of market dynamics from raw material to end-use application:
Secondary research accounts for approximately 25% of our overall methodology and serves as the foundational layer for market understanding, segmentation, and initial data validation. It involves a rigorous and systematic review of published data, industry reports, regulatory frameworks, and corporate intelligence.
Comprehensive Data Sources: Our analysts meticulously extract information from a multitude of reputable sources, including:
Government & Regulatory Bodies: Data, policies, and mandates from national and international environmental protection agencies (e.g., Environmental Protection Agency (EPA), European Chemicals Agency (ECHA) - REACH), and other relevant governmental departments providing insights into sustainability targets and material regulations.
Company Annual Reports and Investor Presentations: For detailed financial performance, strategic initiatives, and product roadmaps of key market players.
Industry Benchmarking: We continuously benchmark market trends, technological advancements, competitive landscapes, and best practices across the global bio-based UV-curable resin industry. This rigorous benchmarking ensures our analysis is grounded in current industry norms and emergent innovations. All secondary data points and market intelligence are updated up to the date of purchase of the report to reflect the latest market dynamics.
Demand Modeling & Market Estimation
Our market sizing and forecasting methodologies integrate both top-down and bottom-up approaches, coupled with multi-level data triangulation, to ensure the highest degree of robustness, accuracy, and reliability in our market figures.
Bottom-Up Approach: This method involves aggregating specific, granular data points to construct the total market size from foundational elements. Key variables and metrics considered for the bio-based UV-curable resin market include:
Production capacity (tonnes/year) and utilization rates of key bio-based UV resin manufacturers globally.
Average selling price (ASP) of distinct bio-based UV resin types (e.g., bio-based epoxy acrylates, bio-based polyester acrylates) segmented by region and formulation.
Consumption volume by major application segments (e.g., coatings, inks, adhesives, 3D printing) and specific end-use industries across various geographical regions.
Estimated penetration rates and adoption trends of bio-based alternatives within specific end-use industry applications (e.g., sustainable packaging, automotive interior components, medical devices).
Top-Down Approach: We validate the bottom-up estimates by evaluating macro-economic factors, overarching industry growth drivers, and broad market trends influencing the global bio-based UV-curable resin market. This involves analyzing global GDP growth, industrial output growth, trends in sustainability mandates, and the impact of regulatory frameworks on sustainable materials adoption.
Multi-Level Data Triangulation: Data points derived from primary interviews are rigorously cross-referenced with secondary research findings and further validated through our internal proprietary databases and advanced statistical models. This iterative and multi-faceted validation process helps to mitigate biases, ensure internal consistency, and enhance the overall reliability and accuracy of our market figures and forecasts.
Data Accuracy & Quality Check
We are committed to delivering highly reliable and actionable market intelligence. Our rigorous quality control processes are designed to ensure an estimated data accuracy level of 88% for all reported figures and forecasts.
Every data point, underlying assumption, and market projection undergoes multiple layers of review by senior analysts and seasoned domain experts to ensure logical coherence and factual integrity.
Proprietary validation models and statistical checks are employed to ensure consistency and coherence across different market segments, geographical regions, and projected timeframes.
The report's entire content, including market dynamics, competitive landscape analysis, and forecast figures, is continuously updated and meticulously verified to reflect the latest information available up to the date of purchase, providing clients with the most current and relevant market insights.
Frequently Asked Questions
1. What environmental regulations influence the bio-based UV-curable resin market?
Increasing global environmental regulations and sustainability mandates drive demand for bio-based solutions. Compliance requirements for volatile organic compounds (VOCs) and hazardous air pollutants (HAPs) favor UV-curable resins. This shift encourages adoption across industries like packaging and automotive.
2. Which end-use industries drive demand for bio-based UV-curable resins?
Packaging, automotive & transportation, and electronics & electrical are key demand sectors. These industries increasingly adopt bio-based UV-curable resins for coatings, inks, and adhesives. This aligns with their sustainability goals and performance requirements.
3. What are the primary application segments for bio-based UV-curable resins?
Coatings, inks, and adhesives & sealants represent significant application segments. The 3D printing sector also shows emerging demand for specialized bio-based UV resins. Bio-based epoxy acrylates and polyurethane acrylates are prominent resin types.
4. How do consumer sustainability preferences impact the bio-based UV-curable resin market?
Growing consumer demand for eco-friendly products pushes brands to adopt sustainable materials. This translates into increased adoption of bio-based UV-curable resins in packaging and consumer goods. Brands aim to meet consumer expectations for reduced environmental footprint.
5. What key challenges hinder the growth of the bio-based UV-curable resin market?
Challenges include higher production costs for bio-based feedstocks and potential performance parity issues compared to petroleum-based alternatives. Ensuring consistent quality and supply chain stability for novel bio-based sources, such as lignin or protein derivatives, also presents hurdles. Market penetration requires overcoming these initial cost and technical barriers.
6. What primary drivers fuel the bio-based UV-curable resin market growth?
The market is driven by increasing environmental awareness and regulatory pressure for sustainable chemicals. Performance benefits like rapid curing and low VOC emissions are significant drivers. This contributes to an 8% projected CAGR, positioning the market to reach $800 million.