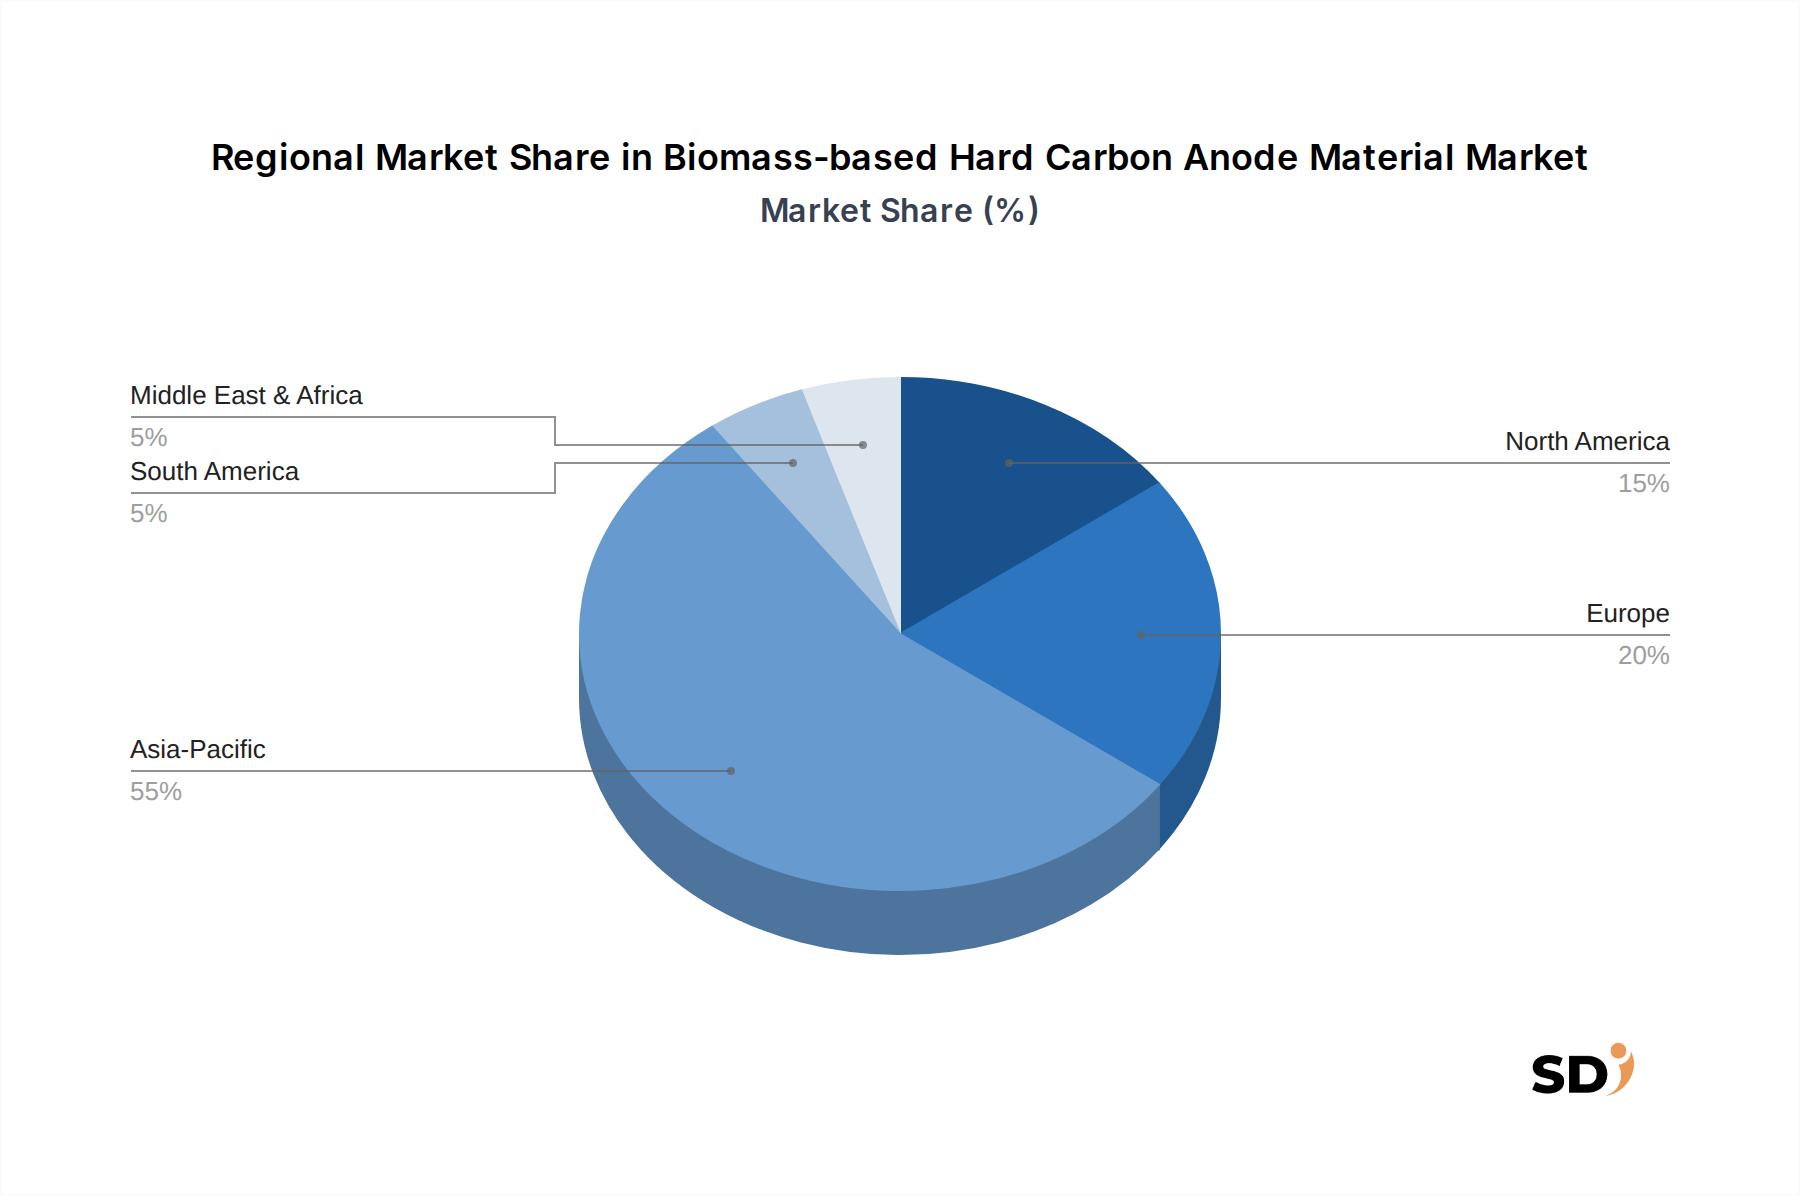
The Biomass-based Hard Carbon Anode Material Market is increasingly influenced by a complex web of global and regional regulatory frameworks and policy initiatives, all aimed at fostering sustainability, supply chain resilience, and technological innovation. Governments worldwide are prioritizing environmental protection and the transition to a circular economy, directly impacting the demand for and development of biomass-derived materials.
In the European Union, the new Battery Regulation (EU) 2023/1542, effective from 2025, is a landmark policy. It mandates strict requirements for battery sustainability, including carbon footprint declarations, minimum recycled content targets, and due diligence obligations for raw material sourcing. This regulation provides a significant tailwind for biomass-based hard carbon, as it offers a renewable, often localized, and lower-carbon alternative to traditional anode materials. It directly encourages investment in the Hard Carbon Anode Market and the broader Battery Materials Market from sustainable sources.
The United States, through initiatives like the Inflation Reduction Act (IRA) of 2022, offers substantial tax credits and incentives for electric vehicles and clean energy technologies, particularly those manufactured with domestically sourced materials. This policy aims to build resilient domestic supply chains and reduce reliance on foreign critical minerals, thereby promoting the development and adoption of biomass-based anode materials. The focus on local content incentivizes the utilization of domestic Biomass Feedstock Market resources.
In Asia Pacific, countries like China, Japan, and South Korea have implemented robust national strategies to support the new energy vehicle industry and advanced battery manufacturing. While these often focus on general battery development, there's a growing emphasis on green manufacturing and resource efficiency. Policies promoting industrial waste utilization and renewable resource development indirectly support the Biomass-based Hard Carbon Anode Material Market. For instance, national five-year plans in China often include targets for sustainable material innovation and circular economy integration, which benefits the Advanced Carbon Materials Market.
Furthermore, global standards bodies and industry alliances are working to establish performance and safety benchmarks for next-generation battery materials, including hard carbon for the Sodium-ion Battery Market. These efforts ensure market confidence and facilitate broader commercial adoption. The overall policy landscape, characterized by environmental stewardship and strategic autonomy in material sourcing, creates a highly favorable environment for the sustained growth and innovation within the Biomass-based Hard Carbon Anode Material Market.